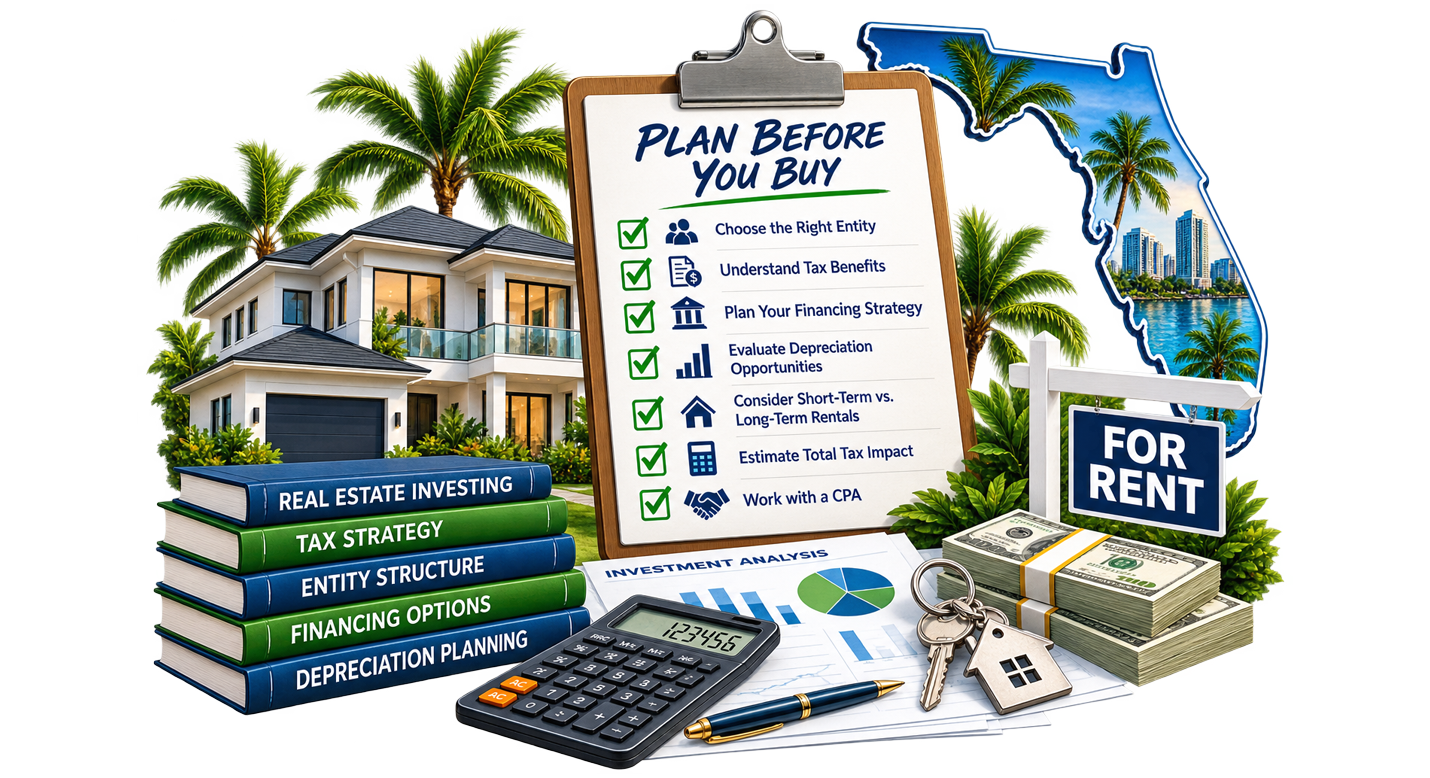
Tax planning should begin before you close on your first Florida rental property. Decisions about ownership structure, financing, purchase-price allocation, depreciation, bookkeeping, property use, and your eventual exit strategy can affect your taxes for years. Planning before the purchase gives you more options and helps avoid costly decisions that may be difficult to reverse later.
Why Should You Talk to a CPA Before Buying Your First Rental Property?
Talking to a CPA before buying your first rental property gives you an opportunity to make tax decisions while you still have options. Once the property has closed, certain choices may become more complicated, costly, or impossible to change without additional tax or legal consequences.
This is the difference between tax preparation and tax planning.
Tax preparation primarily looks backward. Your accountant reviews transactions that have already occurred, calculates your tax liability, and prepares the required tax returns.
Tax planning looks forward. It considers the tax consequences of a transaction before it happens and helps you evaluate how different decisions could affect both your current taxes and your long-term investment strategy.
Buying your first rental property creates several important tax questions at once.
For example, how you own the property can affect your bookkeeping, tax reporting, and future ownership changes. The purchase price and certain acquisition costs help establish the property’s tax basis, which can affect depreciation while you own the property and the calculation of gain or loss when you eventually sell.
You should also consider how the property will be used. A traditional long-term rental, short-term rental, and property with significant personal use can present different tax considerations.
Your CPA can help you think through issues such as:
- Tax deductions: Which operating expenses may be deductible and which costs may need to be capitalized.
- Depreciation: When depreciation begins, which assets are depreciable, and whether strategies such as cost segregation warrant consideration.
- Property basis: How the purchase and qualifying acquisition or improvement costs should be documented for tax purposes.
- Passive losses: Whether rental losses may currently offset other income or could be limited under the passive activity rules.
- Bookkeeping: How to establish your accounts and records correctly from the first transaction.
- Entity structure: Whether individual ownership, an LLC, partnership, or another structure makes sense based on your circumstances.
- Future acquisitions: How the first property fits into a plan for owning multiple rentals.
- Property sales: How depreciation, adjusted basis, potential gain, and strategies such as a 1031 exchange could affect a future disposition.
- Estate planning: How long-term ownership and transfer goals may influence decisions made today.
- Portfolio strategy: How tax planning should evolve as you acquire additional properties and your income changes.
The goal isn’t simply to generate the largest possible deduction in the first year. A decision that reduces taxes today can affect depreciation deductions, taxable income, administrative costs, and the tax consequences of selling the property years later.
Your first rental property should therefore be considered as the beginning of a longer investment strategy rather than an isolated transaction.
For a broader look at how entity structure, depreciation, cost segregation, 1031 exchanges, bookkeeping, and other strategies work together, see our Ultimate Florida Real Estate Investor Tax Planning Guide.
1. Should You Buy the Rental Property Personally or Through an LLC?
Whether to buy a rental property personally or through an LLC is one of the first questions new real estate investors should address. The right choice depends on more than taxes. Liability protection, financing, administrative costs, ownership plans, and how you intend to grow your portfolio can all influence the decision.
One important distinction is that an LLC is a legal entity under state law, but forming an LLC does not automatically change how the property is taxed for federal income tax purposes.
Individual Ownership
The simplest option is purchasing the rental property in your individual name.
This can reduce administrative complexity and may make financing more straightforward in some situations. However, investors should discuss liability exposure and asset-protection considerations with an attorney before deciding that individual ownership is appropriate.
From a federal tax perspective, rental income and expenses from an individually owned property are generally reported on the owner’s individual income tax return, subject to the applicable rental and passive activity rules.
Single-Member LLC
A single-member LLC can provide a separate legal entity for holding the property while potentially maintaining relatively simple federal tax reporting.
Unless it elects otherwise, a domestic single-member LLC is generally treated as a disregarded entity for federal income tax purposes. That means forming the LLC by itself does not necessarily change how the rental property’s income and expenses are reported for federal income tax purposes.
This distinction is important because investors sometimes assume:
LLC = different tax treatment.
That is not necessarily the case.
The LLC may provide legal or organizational benefits while the property’s federal income tax treatment remains similar to direct individual ownership.
Multi-Member LLC and Partnership Taxation
When two or more investors purchase property together through an LLC, the federal tax treatment can become more complex.
A domestic LLC with multiple members is generally classified as a partnership for federal tax purposes unless it elects another available classification.
Partnership taxation introduces additional considerations, including:
- Ownership percentages
- Capital contributions
- Allocations of income and loss
- Distributions
- Partner basis
- Debt allocation
- Partnership tax returns
- Changes in ownership
- Adding or removing partners
If you expect to invest with a spouse, family member, business partner, or outside investor, the ownership and tax structure should ideally be discussed before the property is purchased.
What Is the Difference Between an LLC and Its Federal Tax Classification?
This is one of the most important concepts for new real estate investors to understand.
Legal entity structure and federal tax classification are not the same thing.
For example, depending on its ownership and elections, an LLC may be treated for federal income tax purposes as:
- A disregarded entity
- A partnership
- A corporation
- An S corporation, if eligible and the appropriate election is made
Simply filing documents to create an LLC does not automatically produce a special real estate tax deduction or a lower tax rate.
The tax consequences depend on how the entity is classified, how the property is used, the investor’s overall tax situation, and other applicable tax rules.
What About Liability Protection?
Liability protection is an important reason investors consider LLC ownership, but this is primarily a legal question rather than a tax question.
An attorney can help evaluate issues such as:
- Potential liability associated with rental property ownership
- Separating properties or activities
- Maintaining the LLC correctly
- Contracts and leases
- Insurance
- Asset protection
- Ownership agreements
An LLC should not be treated as a substitute for appropriate insurance, and investors should avoid assuming that merely forming an LLC provides absolute protection in every situation.
What Does an LLC Cost to Maintain?
An LLC can also create expenses and administrative responsibilities that individual ownership may not have.
Depending on the structure, those can include:
- Formation costs
- Florida annual reporting requirements and fees
- Registered agent costs
- Separate bookkeeping
- Separate bank accounts
- Tax preparation costs
- Partnership or corporate tax filings when applicable
- Legal expenses
- Ongoing compliance requirements
For one rental property, these costs should be weighed against the legal, organizational, and tax benefits the structure may provide.
As the portfolio grows, however, a more formal structure may become increasingly useful.
Will an LLC Affect Rental Property Financing?
Potentially.
Financing should be considered before deciding how the property will be titled. Loan terms, underwriting requirements, guarantees, interest rates, and the lender’s willingness to lend directly to an entity can differ from financing obtained by an individual.
An investor should therefore coordinate the ownership decision with the lender rather than creating an entity structure and assuming the financing will work around it.
Changing ownership after closing may also create legal, financing, insurance, and tax considerations that should be reviewed before transferring the property.
What If You Plan to Add a Partner Later?
Your future plans matter too.
If you expect to bring another investor into the property later, consider that possibility when establishing the original structure.
Adding a partner can affect:
- Ownership percentages
- Tax classification
- Tax basis
- Capital accounts
- Profit and loss allocations
- Debt
- Property title
- Financing
- Operating agreements
- Tax reporting
Planning for future ownership changes before purchasing the property can be easier than restructuring an established investment later.
Should Your CPA or Attorney Decide How You Own the Property?
Ideally, both should be involved in their respective areas of expertise.
A CPA can evaluate the federal and state tax consequences, reporting requirements, bookkeeping implications, and how the property fits into your broader tax strategy.
An attorney can advise on legal ownership, liability protection, operating agreements, asset protection, and other legal considerations.
The best structure for another investor isn’t automatically the best structure for you. Someone purchasing one long-term rental with conventional financing can have very different needs from an investor building a ten-property portfolio with multiple partners.
Choose the ownership structure based on your property, financing, tax situation, liability considerations, and long-term investment strategy—not simply because another real estate investor told you that every rental property should be placed in an LLC.
For a deeper comparison of common ownership and tax structures, see LLC vs. S Corp Structures for Florida Real Estate Investors.
2. Should a Rental Property Be Owned by an S Corporation?
An S corporation can provide tax advantages for certain active businesses, but that does not mean it is automatically the best structure for owning rental real estate. Investors should consider the type of activity, expected appreciation, financing, future property transfers, and long-term exit strategy before placing a rental property in an S corporation.
One reason for the confusion is that investors often hear that an S corporation can “save self-employment taxes.” That can be true in certain active businesses where an owner performs services and receives business profits subject to the applicable employment tax rules.
Traditional rental real estate, however, generally operates differently.
Does an S Corporation Reduce Taxes on Rental Income?
Not automatically.
Rental income is generally not subject to self-employment tax in the same way as income from many active trades or businesses, although exceptions can apply depending on the activity and services provided.
As a result, putting a traditional rental property into an S corporation does not automatically create the same potential employment-tax benefit that an S corporation may provide for certain operating businesses.
That is why the question should not simply be:
“Can an S corporation save taxes?”
Instead, ask:
“What tax problem am I trying to solve by using an S corporation for this particular property?”
If there is no clear answer, the additional complexity may not provide the benefit the investor expects.
Why Does Property Appreciation Matter?
Real estate investors typically hope their properties increase in value.
That potential appreciation makes long-term ownership structure especially important.
If appreciated property is held inside an S corporation and the investor later wants to distribute or transfer the property out of the corporation, the transaction can potentially trigger taxable gain even though the investor did not complete a traditional sale to an unrelated buyer.
This can reduce flexibility compared with structures in which property can potentially be transferred under different tax rules.
The issue may not matter when the property is purchased, but it can become very important years later after significant appreciation has occurred.
Why Should You Think About the Exit Before Choosing an S Corporation?
Before selecting an entity, consider what might eventually happen to the property.
For example:
- Will you hold it for decades?
- Could you bring in another investor?
- Might you transfer the property to another entity?
- Could you eventually sell it?
- Are you considering a future 1031 exchange?
- Could the property become part of an estate plan?
- Might your investment strategy change as your portfolio grows?
A structure that appears convenient today can create limitations later.
That is particularly important with appreciating real estate because restructuring after substantial appreciation has occurred can have very different tax consequences from establishing the appropriate structure before the property is acquired.
When Can an S Corporation Still Be Useful for Real Estate Investors?
An S corporation can still play an important role in a real estate investor’s overall business structure.
For example, an investor may operate a separate active business related to real estate—such as certain management, brokerage, construction, or other service activities—where an S corporation warrants consideration based on the specific facts.
That does not necessarily mean the appreciating rental properties themselves should be held inside that same entity.
In some situations, investors separate an active operating business from the entities that own their investment properties. The appropriate arrangement depends on the investor’s activities, ownership, liability considerations, and tax situation.
Should You Put Your First Rental Property in an S Corporation?
There is no universal answer, but investors should not choose an S corporation simply because they have heard that it “saves taxes.”
Before making the election, evaluate:
- How the rental income will be taxed
- Whether there is actually an employment-tax benefit
- Expected property appreciation
- Future ownership changes
- Potential property distributions or transfers
- Financing
- Administrative and payroll requirements
- Future sales
- 1031 exchange plans
- Estate and succession goals
- Other real estate businesses you operate
The appropriate structure should support the investment’s entire lifecycle—not simply minimize one category of tax in the first year.
A CPA can analyze the tax consequences while an attorney can evaluate liability protection and legal ownership considerations. Coordinating both before purchasing the property can prevent an investor from choosing a structure that becomes difficult or expensive to unwind later.
For a more detailed comparison, see LLC vs. S Corp Structures for Florida Real Estate Investors.
3. How Does Financing Affect Your Rental Property Taxes?
How you finance a rental property can affect the timing and treatment of several tax-related costs. Your down payment, mortgage interest, loan fees, points, refinancing costs, and financing arrangements with partners or private lenders should all be properly documented from the beginning.
One of the most important distinctions for new investors is the difference between mortgage principal and mortgage interest.
Is the Down Payment on a Rental Property Tax Deductible?
Generally, your down payment is not a current rental property expense deduction.
Instead, the down payment represents part of the money you contribute toward purchasing the property. The tax basis of the property is determined under applicable tax rules and is not simply equal to the amount of cash you put down.
For example, putting $100,000 down on a $500,000 rental property does not mean you depreciate only $100,000. Likewise, the $100,000 down payment generally is not deducted from your rental income in the year of purchase.
The property’s basis, allocation between land and depreciable property, acquisition costs, and other adjustments must be determined separately.
What Is the Difference Between Mortgage Principal and Mortgage Interest?
A typical mortgage payment can contain several components, including:
- Principal
- Interest
- Property taxes through escrow
- Insurance through escrow
- Other applicable charges
These amounts should not simply be recorded as one “mortgage expense.”
Mortgage principal reduces the amount you owe the lender. Paying down principal generally does not create a current rental expense deduction.
Mortgage interest, on the other hand, may generally be deductible when the debt and use of the proceeds satisfy the applicable tax requirements.
For example, if a $3,000 monthly payment consists of $1,700 of principal and $1,300 of interest, you generally would not treat the entire $3,000 as mortgage interest expense.
Your bookkeeping should separate the components correctly.
Can You Deduct Mortgage Interest on a Rental Property?
Interest on debt associated with acquiring or operating a rental property may generally be deductible, subject to applicable tax rules and limitations.
The tax treatment can depend on factors such as:
- How the borrowed money was used
- The investor’s activities
- The type of debt
- Business interest limitations where applicable
- Personal versus rental use
- Refinancing and use of refinancing proceeds
This is another reason investors should maintain clear records showing where borrowed funds went rather than assuming every interest payment connected with a rental property receives identical tax treatment.
Are Loan Origination Fees Deductible?
Loan origination costs require separate analysis.
Certain costs associated with obtaining financing generally are not treated the same way as ordinary operating expenses. Instead of receiving an immediate deduction, some financing costs may need to be capitalized and deducted over the life of the loan.
Investors should therefore keep the loan closing disclosure and supporting documents showing individual financing charges.
Do not simply categorize every cost appearing on the closing statement as a current-year expense.
Can You Deduct Points Paid on a Rental Property Loan?
Points paid to obtain financing for rental property generally do not receive the same treatment that may apply to qualifying points on certain principal-residence mortgages.
For rental property, points and similar financing costs may generally need to be deducted over the term of the loan rather than entirely in the year they are paid, depending on the circumstances.
Your CPA should review the loan documents and determine the appropriate treatment.
What Happens to Financing Costs When You Refinance?
Refinancing creates another set of tax and accounting considerations.
A refinance can involve:
- New loan origination costs
- Points
- Appraisal fees
- Legal or closing costs
- Payoff of the previous mortgage
- Cash-out proceeds
- Remaining unamortized financing costs from the old loan
The tax treatment of these items can differ.
Cash received through refinancing also is generally not automatically taxable income simply because money enters your bank account. It represents borrowed funds that generally must be repaid.
However, how those borrowed funds are subsequently used can matter for determining the tax treatment of the related interest.
For example, using cash-out refinancing proceeds for another investment can present different tax considerations from using the money for personal expenses.
Keep records tracing where refinancing proceeds were used.
What If You Use a Private Loan to Buy the Property?
Not every real estate investor obtains financing from a traditional bank.
Investors may use:
- Private lenders
- Hard-money lenders
- Seller financing
- Loans from family members
- Business lines of credit
- Other financing arrangements
The fact that financing comes from a private source does not eliminate the need for proper documentation.
The agreement should clearly establish relevant terms such as the principal amount, interest rate, repayment requirements, and other loan provisions.
Investors should also maintain records of payments and interest rather than relying on informal arrangements that become difficult to document at tax time.
What If a Partner Helps Finance the Property?
Partner financing requires particular care because money entering the investment may represent different things.
For example, funds provided by another investor could potentially represent:
- A capital contribution
- A loan to the entity
- A loan to another partner
- An ownership investment
- Some combination of financing and equity
These classifications can have different accounting, tax, and legal consequences.
Before accepting money from a partner, establish:
- Who owns the property
- Ownership percentages
- How much each person contributes
- Whether contributed funds are debt or equity
- Who is responsible for the mortgage
- How profits and losses will be allocated
- How distributions will work
- What happens if additional capital is needed
These arrangements should be coordinated with both your CPA and attorney and properly reflected in the entity’s books and governing agreements.
Why Should Financing Be Part of Tax Planning Before Closing?
Financing is not just about determining whether you can afford the monthly payment.
It can affect your:
- Cash investment
- Interest deductions
- Property bookkeeping
- Loan-cost deductions
- Tax basis calculations
- Partner accounting
- Cash flow
- Future refinancing
- Ability to acquire additional properties
Before closing, provide your CPA with the expected purchase and financing information so the transaction can be recorded correctly from the beginning.
Most importantly, remember that borrowing $400,000 does not create a $400,000 tax deduction, and repaying $400,000 of mortgage principal generally does not create $400,000 of current rental expenses.
The tax benefits associated with rental property come from the applicable deductions, depreciation, and other tax rules—not simply from the amount borrowed or repaid.
5. Why Should You Review the Closing Statement With Your CPA?
Your rental property’s closing statement contains much more than the purchase price and the amount of cash you brought to closing. It provides information your CPA may need to establish the property’s tax basis, record the acquisition correctly, identify financing costs, account for prorated expenses, and set up accurate depreciation and bookkeeping records.
For that reason, the closing statement should be one of the first documents you provide to your CPA after purchasing a rental property.
Why Isn’t the Cash You Paid at Closing the Property’s Cost?
A common bookkeeping mistake is recording the amount of cash paid at closing as though it represents the property’s total cost.
It doesn’t.
For example, an investor might purchase a $500,000 property using:
- $100,000 down payment
- $400,000 mortgage financing
- Additional cash for closing costs and escrow deposits
The fact that the investor contributed approximately $100,000 toward the purchase does not mean the property should be recorded in the books as a $100,000 asset.
Likewise, the mortgage proceeds are not rental income simply because borrowed funds helped purchase the property.
The accounting needs to reflect the property acquired, debt incurred, cash contributed, and individual closing costs according to their proper treatment.
What Information Does the Closing Statement Provide?
Depending on the transaction, the settlement or closing statement may include:
- Purchase price
- Earnest money or deposits
- Mortgage proceeds
- Down payment
- Property tax prorations
- Loan origination charges
- Points
- Title-related expenses
- Recording fees
- Transfer-related charges
- Prepaid insurance
- Escrow deposits
- Seller credits
- Buyer credits
- HOA-related amounts
- Interest adjustments
- Other acquisition and financing costs
These items do not necessarily receive the same tax treatment.
Some may affect the property’s basis. Some may relate to financing. Some may represent prepaid expenses. Others may be escrow deposits, prorated costs, or amounts that receive separate tax treatment.
That’s why the closing statement should be analyzed rather than entered into the accounting system as one transaction labeled “property purchase.”
How Do Property Tax Prorations Affect the Accounting?
Real estate transactions frequently include adjustments between the buyer and seller for property taxes and other expenses.
For example, the seller may have effectively borne responsibility for property taxes attributable to the portion of the year before closing, while the buyer is responsible for the period after acquiring the property.
The closing statement may include credits or debits designed to allocate these amounts between the parties.
These adjustments need to be understood when establishing the accounting records rather than automatically categorizing every tax-related amount shown on the statement as the buyer’s property tax expense.
How Should Loan Costs Be Treated?
Financing costs should also be separated from the cost of acquiring the property.
The closing documents may show items such as:
- Loan origination fees
- Points
- Lender charges
- Mortgage-related legal fees
- Credit report fees
- Other financing expenses
Some financing costs may need to be capitalized and deducted over the applicable loan period rather than deducted immediately or added to the property’s depreciable basis.
This distinction becomes especially important when the property is refinanced or the loan is paid off before its original maturity.
Keeping the original closing and loan documents allows your CPA to track these costs correctly.
What About Title and Recording Costs?
Certain title, legal, recording, and other acquisition-related costs may affect the property’s basis, depending on the nature of the expense.
The important question is what the particular cost was for.
A legal fee incurred to acquire property, for example, may receive different treatment from a legal fee incurred later to resolve an operating issue involving a tenant.
Similarly, a cost associated with obtaining financing may receive different treatment from a cost directly associated with acquiring title to the property.
Your CPA should therefore review individual line items rather than applying one tax treatment to every closing cost.
Are Escrow Deposits Deductible?
Amounts placed into escrow at closing generally should not automatically be recorded as current rental property expenses.
An escrow account may hold funds that the lender later uses to pay:
- Property taxes
- Insurance
- Other required expenses
Putting money into the escrow account and the escrow account subsequently paying an expense are separate events.
Recording both as expenses can result in double counting.
Accurate bookkeeping should distinguish between funds being deposited into escrow and actual deductible expenses being paid.
How Should Prepaid Insurance Be Recorded?
Rental property insurance may also appear on the closing statement.
If the investor pays an insurance premium in advance, the tax and accounting treatment may depend on the coverage period and applicable rules.
It should not automatically be treated as part of the building’s depreciable basis simply because the payment occurred at closing.
Your CPA can determine the appropriate treatment based on what the payment represents.
Why Do Seller Credits and Other Adjustments Matter?
Seller credits can reduce the buyer’s cash requirement at closing, but the tax consequences depend on what the credit represents.
Likewise, prorations and adjustments can relate to:
- Property taxes
- Rent collected before closing
- Security deposits
- HOA fees
- Utilities
- Repairs
- Closing concessions
- Other property-related amounts
These adjustments can affect how the acquisition should be recorded.
For an occupied rental property, the closing documents may also show tenant deposits or rental-income adjustments that need to be reflected correctly in the new owner’s books.
How Should the Property Purchase Be Entered Into QuickBooks?
A rental property purchase generally should not be entered as:
“Property Purchase Expense — $100,000.”
Instead, the accounting should reflect the different components of the transaction.
Depending on the facts, the books may need separate entries for:
- Land
- Building
- Other acquired assets
- Mortgage or other debt
- Owner contribution
- Acquisition costs
- Financing costs
- Property tax adjustments
- Insurance
- Escrow
- Credits and prorations
The exact entries depend on the transaction.
This is especially important because the accounting records should ultimately reconcile to the closing statement.
Why Does Getting the Closing Entry Right Matter Later?
Errors made when the property is first entered into the books can follow the investor for years.
An incorrect closing entry can potentially lead to:
- Incorrect property basis
- Incorrect depreciation
- Missing acquisition costs
- Incorrect loan balances
- Duplicate expenses
- Incorrect escrow accounting
- Poor property-level financial statements
- Problems calculating gain when the property is sold
If the investor later completes a 1031 exchange, refinances the property, brings in a partner, or sells after substantial appreciation, reconstructing an inaccurate acquisition years later can become even more difficult.
What Should You Send Your CPA After Closing?
After purchasing a rental property, provide your CPA with the complete transaction file, including:
- Signed purchase agreement
- Final settlement or closing statement
- Loan closing disclosure
- Promissory note and mortgage documents
- Title documents
- Appraisal, when relevant
- Property tax information
- Insurance documents
- HOA information
- Entity documents, if an LLC or partnership owns the property
- Invoices for acquisition-related professional services
- Records of renovations or improvements beginning immediately after closing
Your CPA can then determine how the transaction should be reflected in your books and tax records.
The key is to avoid waiting until tax season. Reviewing the closing statement shortly after purchasing the property helps establish accurate basis, depreciation, debt, and bookkeeping records from day one—before small accounting errors become long-term tax problems.
6. How Should You Allocate the Purchase Price Between Land and Building?
When you buy a rental property, the purchase price generally needs to be allocated between the land and the depreciable property. This allocation matters because land generally cannot be depreciated, while a rental building generally can. Assigning the purchase price incorrectly can therefore affect your depreciation deductions for years.
For example, buying a rental property for $500,000 does not automatically give you $500,000 of depreciable building basis. If part of that value is attributable to land, the land portion generally must be excluded from the amount depreciated.
Why Isn’t Land Depreciable?
Depreciation is intended to account for the exhaustion, wear and tear, or obsolescence of property used to produce income.
A rental building has a determinable useful life for tax purposes and generally depreciates under the applicable tax rules.
Land is different. Land generally does not have a determinable useful life and therefore is not depreciated.
That means an investor needs to distinguish between:
Land — generally nondepreciable
and
Building and other qualifying depreciable property — potentially depreciable
This allocation should be established when the property is placed into the investor’s tax and accounting records.
Why Does the Allocation Matter So Much?
Consider a simplified example.
An investor purchases a rental property for $500,000.
If a supportable allocation results in:
- Land: $100,000
- Building: $400,000
the $100,000 allocated to land generally would not be depreciated, while the building portion may generally form part of the depreciable basis, subject to applicable adjustments and tax rules.
Now imagine the investor arbitrarily records:
- Land: $10,000
- Building: $490,000
That allocation produces a larger depreciable amount and therefore potentially larger depreciation deductions.
But investors cannot simply choose whichever allocation creates the biggest tax deduction. The allocation should be reasonable and supportable based on the facts and circumstances.
How Can You Determine the Value of the Land and Building?
There is no single allocation method that automatically applies appropriately to every property.
Depending on the facts, information considered when establishing or evaluating the allocation may include:
- Property tax assessment information
- County property appraiser records
- Appraisals
- Purchase documentation
- Comparable land values
- Independent valuations
- Information about the property and improvements
- Other relevant evidence supporting relative values
For a Florida property, county property appraiser records may provide separate assessed values for land and improvements. Those figures can provide useful information, but assessed values are not necessarily the same as the property’s actual purchase price or fair market value.
The appropriate approach should therefore be evaluated based on the particular transaction rather than automatically copying one number from a public record.
Can You Use the County Property Appraiser’s Land Value?
Property appraiser records can be useful evidence when evaluating an allocation, particularly because they often separately identify land and building or improvement values.
However, investors should understand what those numbers represent.
An assessed value used for property tax purposes may differ from:
- The property’s purchase price
- Fair market value
- An independent appraisal
- The property’s actual land and improvement values at the time of acquisition
One potential approach is to consider the relative relationship between land and improvements shown in reliable valuation information rather than assuming the assessed dollar amounts themselves equal the investor’s tax basis.
The appropriate methodology should be reviewed with a tax professional based on the property’s facts.
What If You Have an Appraisal?
An appraisal obtained as part of the purchase or financing process may contain useful information about the property’s land and improvements.
Depending on the appraisal, it may provide:
- Site value
- Improvement value
- Comparable property information
- Replacement-cost information
- Details about buildings and other improvements
Keep the appraisal with your permanent acquisition records and provide it to your CPA when establishing the property’s basis.
It may become valuable documentation supporting the allocation used for tax purposes.
What About Furniture, Appliances and Other Assets?
Not every dollar allocated away from land necessarily belongs in one building account.
A rental property acquisition can sometimes include other assets, such as:
- Furniture
- Appliances
- Equipment
- Certain land improvements
- Other qualifying property components
These assets may potentially have different depreciation treatment from the building itself.
For a furnished short-term rental, for example, the acquisition may involve substantially more separately identifiable personal property than the purchase of an unfurnished long-term rental.
This is also one of the reasons some investors evaluate a cost segregation study, which can identify qualifying components that may be depreciated over shorter recovery periods than the building.
Why Shouldn’t You Assign the Lowest Possible Amount to Land?
Because the objective isn’t to create the largest depreciation deduction possible.
The objective is to establish a defensible tax position supported by the facts.
Assigning an artificially low amount to land can increase the building’s depreciable basis and produce larger depreciation deductions. But if the allocation cannot be supported, those deductions may be challenged.
An investor purchasing a property on valuable Florida land, for example, should be particularly cautious about using a nominal land allocation simply because it produces a better tax result.
The fact that an allocation is favorable does not make it incorrect—but it should have reasonable support.
Does the Allocation Affect the Property When You Eventually Sell?
Yes.
Depreciation affects adjusted basis, and adjusted basis is important when determining the tax consequences of a future property sale.
An aggressive allocation that increases depreciation today can therefore have consequences later.
This illustrates a broader principle of real estate tax planning:
The largest current deduction is not always the only consideration.
Investors should evaluate current tax savings alongside:
- Expected holding period
- Future depreciation
- Property appreciation
- Potential sale
- Depreciation-related tax consequences
- 1031 exchange plans
- Overall investment strategy
Should the Allocation Be Established Immediately After Purchase?
Yes. The best time to establish and document the allocation is when the property is acquired and the records are readily available.
Keep:
- Closing statement
- Purchase agreement
- Appraisal
- Property appraiser information
- Property description
- Improvement information
- Relevant valuation documentation
- Records of furniture or equipment acquired with the property
Provide these documents to your CPA when the property is added to your accounting and depreciation records.
Establishing a reasonable allocation between land, building, and any other qualifying property components from the beginning helps ensure that depreciation is calculated correctly and gives you documentation supporting the tax treatment used throughout the property’s ownership.
Clarify the $500,000 exampleAdd a practical allocation workflow
7. When Does Depreciation Begin on a Rental Property?
Depreciation generally begins when a rental property is placed in service, not simply on the date you purchase or close on the property. For a rental, that generally means the property is ready and available for its intended use as a rental property.
Understanding this distinction is important because the placed-in-service date helps determine when depreciation begins and affects the amount of depreciation that may be claimed for the first year.
What Does “Placed in Service” Mean for a Rental Property?
A rental property is generally considered placed in service when it is ready and available to rent.
The property does not necessarily need to have a tenant physically occupying it before depreciation can begin. If the property is ready for tenants and genuinely available for rent, it may be placed in service even if you are still searching for the first tenant.
For example, suppose you close on a rental property on March 15. The property is already in rentable condition, and you immediately list it for rent and begin accepting applications.
Even if the first tenant does not move in until April, the relevant placed-in-service date may occur when the property became ready and available for rent rather than when the tenant moved in.
The specific facts and circumstances matter, so investors should document when the property actually became available for its intended rental use.
What If the Property Is Ready to Rent Immediately After Closing?
Consider an investor who purchases a turnkey rental property.
The property:
- Is in good condition
- Requires no significant renovations
- Has working utilities
- Meets applicable rental requirements
- Is immediately advertised for rent
- Is available for tenants
In that situation, the property may be placed in service shortly after acquisition because it is ready and available for rental use.
The investor should retain evidence supporting that date, such as the rental listing, property management agreement, photographs, correspondence, or other records showing when the property became available.
What If the Property Needs Major Renovations First?
Now consider a different investor who purchases a property on March 15 but immediately begins a substantial renovation.
The property requires:
- A new kitchen
- Bathroom renovations
- Major flooring work
- Electrical repairs
- Plumbing work
- Significant construction
The work continues for several months, and the property is not ready or available to tenants until August.
In this situation, simply owning the property since March does not necessarily mean building depreciation begins in March.
The property may not be placed in service until it is actually ready and available for its intended rental use.
This is why investors should distinguish among three dates:
Purchase date
Placed-in-service date
Tenant move-in date
Those dates can be different.
Does the Property Need to Be Occupied Before Depreciation Begins?
Not necessarily.
A rental property can generally be ready and available for rent even though a tenant has not yet signed a lease or moved in.
For example, suppose renovations are completed on September 1 and the property is listed for rent immediately. The investor actively markets the property, shows it to prospective tenants, and is willing to accept a qualified renter.
The first tenant does not move in until October 15.
The fact that the property remained vacant during September does not automatically mean depreciation must wait until October 15. What matters is when the property became ready and available for its intended rental use.
What About Minor Repairs Before Renting the Property?
Not every repair automatically delays the placed-in-service date.
There is a meaningful difference between a property that is unavailable because it is undergoing substantial work and a rental that is already ready and available but receives ordinary maintenance or minor repairs.
The determination depends on the property’s actual condition and circumstances.
Investors should therefore avoid assuming either:
“I closed, so depreciation starts immediately.”
or
“I don’t have a tenant yet, so depreciation cannot start.”
Neither statement is universally correct.
Why Does the Placed-in-Service Date Affect First-Year Depreciation?
Rental property depreciation is calculated using applicable tax conventions and recovery periods. As a result, the month or year in which an asset is placed in service can affect the amount of depreciation available during the first tax year.
This applies not only to the building but also to other depreciable assets that may be placed in service at different times.
For example, you might have:
- Rental building placed in service in August
- Appliances installed and placed in service in August
- Furniture purchased and placed in service in September
- Additional equipment placed in service in November
These assets should not automatically be assigned the property’s closing date simply because they relate to the same investment.
Accurate placed-in-service records allow the depreciation schedule to reflect what actually occurred.
How Does the Placed-in-Service Date Affect Renovations and Improvements?
Improvements can have their own placed-in-service dates.
Suppose you already operate a rental property and complete a major qualifying improvement during the year.
The improvement generally does not begin being depreciated merely because you paid a contractor a deposit or received an invoice. The relevant timing generally depends on when the improvement is completed and placed in service.
This is another reason investors should track major improvements separately rather than combining them with ordinary repairs and maintenance.
For each significant capital asset or improvement, retain:
- Description
- Cost
- Invoice
- Payment records
- Completion date
- Placed-in-service date
- Property associated with the expenditure
What Records Can Help Establish the Placed-in-Service Date?
Keep documentation showing when the property became ready and available for rental use.
Useful records may include:
- Online rental listing
- Property management agreement
- Leasing correspondence
- Photographs
- Contractor completion documents
- Certificates or permits where applicable
- Utility records
- Inspection records
- Advertising invoices
- Tenant applications
- Lease documents
No single document necessarily determines the answer in every situation. The goal is to maintain contemporaneous evidence showing what happened.
Why Is Documenting the Date Important?
If the placed-in-service date is incorrect, the depreciation schedule may also be incorrect.
Starting depreciation too early could result in deductions being claimed before the property qualified.
Starting too late could cause an investor to miss depreciation that may have been available.
And because depreciation affects the property’s adjusted tax basis, errors can continue to matter when the property is eventually sold.
Instead of trying to reconstruct the timeline years later, document the property’s status while the events are occurring.
What Should You Tell Your CPA?
When providing information about a newly acquired rental property, don’t give your CPA only the closing date.
Also provide:
- Date purchased
- Condition at acquisition
- Renovation period, if any
- Date major work was completed
- Date property became ready to rent
- Date first advertised
- Date first tenant signed a lease
- Date first tenant occupied the property
- Dates furniture, appliances, equipment, and improvements were placed in service
Your CPA can then determine the appropriate tax treatment based on the facts.
The key takeaway is simple: buying a rental property and placing it in service are not necessarily the same event. Establishing and documenting the correct placed-in-service date helps ensure depreciation begins at the appropriate time and that your depreciation schedule is accurate from the first year.
For a deeper look at depreciation planning, see Four Depreciation Strategies for Florida Rental Property Investors.
8. Should You Consider Cost Segregation When Buying Your First Rental?
Cost segregation can help some rental property investors accelerate depreciation deductions by identifying portions of a property that may qualify for shorter recovery periods than the building itself. However, a cost segregation study is not automatically worthwhile simply because you purchased rental real estate.
The decision should consider the property’s value and components, your current tax position, how long you expect to own the property, the cost of the study, and the potential tax consequences when the property is eventually sold.
What Does a Cost Segregation Study Do?
Without cost segregation, much of a residential rental property’s depreciable building basis is generally depreciated over the recovery period applicable to residential rental property.
A cost segregation study takes a more detailed look at the property.
Instead of treating most depreciable costs as part of one building, the study identifies qualifying components that may be classified into different asset categories with shorter recovery periods.
Depending on the property, those components can potentially include certain:
- Flooring
- Cabinetry or specialized finishes
- Electrical components serving qualifying equipment
- Furniture and fixtures
- Appliances
- Site improvements
- Landscaping-related improvements
- Parking areas
- Fencing
- Other qualifying property components
The specific classifications depend on the property’s facts and applicable tax rules.
How Can Cost Segregation Accelerate Depreciation?
The primary benefit is timing.
Cost segregation generally does not create depreciation out of nothing. Instead, it can move some depreciation deductions from later years into earlier years by identifying assets that qualify for shorter recovery periods.
For example, instead of recovering the cost of a qualifying component over the building’s longer depreciation period, that component may potentially be depreciated over a shorter period.
That can increase depreciation deductions during the earlier years of ownership and potentially reduce current taxable income.
The resulting tax savings may improve cash flow that the investor can use for:
- Additional investments
- Property improvements
- Debt reduction
- Reserves
- Other business purposes
But accelerating a deduction is different from permanently eliminating tax. The long-term consequences should also be considered.
Does Bonus Depreciation Make Cost Segregation More Valuable?
Potentially.
Certain shorter-lived assets identified through a cost segregation study may qualify for bonus depreciation when the applicable requirements are met.
The bonus depreciation rules have changed repeatedly, so investors should use the rules applicable to the year in which the property or qualifying assets are placed in service rather than relying on an old article or another investor’s previous tax strategy.
This can significantly affect the economics of a cost segregation study.
Your CPA should model the expected deductions using the rules applicable to your particular tax year.
What Types of Properties May Be Worth Evaluating?
Cost segregation can potentially apply to different types of income-producing real estate, including:
- Residential rental properties
- Short-term rentals
- Multifamily properties
- Commercial buildings
- Office properties
- Retail properties
- Industrial properties
- Other qualifying investment real estate
However, being eligible for cost segregation does not necessarily mean paying for a study makes financial sense.
A relatively inexpensive rental with few separately identifiable components may produce a much smaller benefit than a high-value property with significant improvements and shorter-lived assets.
The potential benefit should be compared with the cost and complexity of the study.
Why Does Property Value Matter?
Cost segregation studies require time and expertise, and professional studies can involve meaningful costs.
As property value and depreciable basis increase, there may be more dollars available to reclassify into shorter-lived asset categories, potentially making the strategy more economically attractive.
Consider two properties:
Property A: $180,000 rental with a relatively small depreciable basis.
Property B: $1.5 million rental with substantial building improvements, site improvements, furniture, and other qualifying components.
Even if both properties are technically candidates for cost segregation, the potential tax benefit can be dramatically different.
There is no universal purchase-price threshold at which cost segregation suddenly becomes worthwhile. The appropriate decision depends on the expected benefit relative to the cost.
Why Does Your Personal Tax Position Matter?
A large depreciation deduction is useful only within the context of the tax rules that determine how and when you can use it.
For many investors, rental real estate is subject to the passive activity loss rules.
Suppose a cost segregation study creates an additional $80,000 of depreciation and causes the rental to report a substantial tax loss.
That does not automatically mean the investor can deduct the entire $80,000 against W-2 wages or other nonpassive income.
The ability to use rental losses can depend on factors including:
- Passive income
- Active participation
- Income limitations
- Material participation
- Real Estate Professional Status
- The nature of the rental activity
- Other investments and activities
An investor who can currently use accelerated depreciation may receive a different near-term benefit from an investor whose additional losses become suspended.
Suspended losses are not necessarily lost, but the timing of the tax benefit changes.
That is why cost segregation should be evaluated as part of the investor’s overall tax plan, not as an isolated depreciation strategy.
Does Cost Segregation Make Sense for a First-Time Investor?
It can, but the answer depends on the property and the investor.
Before commissioning a study, consider:
- Purchase price
- Depreciable basis
- Property type
- Amount of land value
- Building components
- Renovations
- Furniture and equipment
- Current taxable income
- Passive income
- Ability to use additional losses
- Cost of the study
- Applicable depreciation rules
- Expected ownership period
- Future sale plans
For some first-time investors, cost segregation may provide significant value.
For others, standard depreciation may be entirely appropriate.
The fact that cost segregation is available does not mean you need to use it.
How Does Your Expected Holding Period Affect the Decision?
How long you expect to own the property should be part of the analysis.
An investor planning to hold a property for decades may evaluate accelerated depreciation differently from an investor expecting to sell within two or three years.
Cost segregation generally accelerates deductions into earlier periods. That timing benefit can be valuable, but selling assets after claiming accelerated depreciation can create additional tax considerations.
Your CPA should therefore consider not only:
“How much can I deduct this year?”
but also:
“What happens when I eventually dispose of the property?”
What Happens When You Sell a Property After Cost Segregation?
A future sale can involve tax consequences related to depreciation previously claimed.
Different asset categories can also be subject to different rules when disposed of.
That does not mean cost segregation is a bad strategy. It means the strategy should be evaluated over the expected lifecycle of the investment rather than based solely on the first-year deduction.
A useful analysis may compare:
- Current tax savings
- Timing value of accelerated deductions
- Expected holding period
- Future depreciation
- Potential disposition consequences
- Expected future tax rates
- Alternative uses of the resulting cash flow
A strategy that generates significant current tax savings can still make sense even when future tax consequences exist, but those consequences should be understood beforehand.
Should You Do the Cost Segregation Study Immediately After Purchase?
The acquisition of a property is a logical time to evaluate cost segregation because the investor is already establishing basis and depreciation records.
However, an investor who did not perform a study in the acquisition year may still have options later.
Under certain circumstances, a cost segregation study can be performed on a property placed in service in an earlier year, with applicable tax procedures used to address the change in depreciation treatment.
That means investors should not assume they permanently missed the opportunity simply because they did not complete a study immediately after closing.
The appropriate procedure should be determined with a qualified tax professional.
What Information Is Needed to Evaluate Cost Segregation?
Before deciding, gather:
- Closing statement
- Purchase price
- Land/building allocation
- Appraisal
- Building plans when available
- Property description
- Renovation records
- Contractor invoices
- Improvement costs
- Furniture and equipment records
- Placed-in-service date
Your CPA can then estimate whether the potential tax benefit warrants obtaining a professional cost segregation study.
What Should You Ask Your CPA Before Ordering a Study?
Before spending money on cost segregation, ask:
- How much depreciable basis does this property have?
- Approximately how much basis might be reclassified?
- What depreciation rules apply this year?
- Can I currently use the additional deductions?
- Could the deductions become passive suspended losses?
- How long do I expect to own the property?
- What could happen tax-wise when I sell?
- How much will the study cost?
- What is the estimated current tax benefit?
- Does cost segregation fit my broader investment strategy?
The goal is not to generate the largest depreciation number possible. It is to determine whether accelerating depreciation creates a meaningful economic benefit for your particular situation.
Cost segregation can be a powerful strategy for the right property and investor, but it should be evaluated before implementation rather than treated as an automatic step every time rental real estate is purchased.
For a complete explanation of the strategy, see Cost Segregation for Florida Real Estate Investors.
9. What Renovations Should You Plan Before Buying the Property?
If a rental property will need renovations soon after purchase, those costs should be considered before closing—not only for budgeting, but also for tax and recordkeeping purposes. The way improvements are documented and classified can affect basis, depreciation, deductions, and future gain calculations.
Investors should identify likely work before buying so they can separate the property’s original condition from improvements made after acquisition.
Which Renovations Should You Identify Before Closing?
Common projects include:
- Roof replacement
- HVAC replacement or major repair
- Kitchen renovation
- Bathroom renovation
- Flooring
- Appliances
- Landscaping
- Furniture
- Electrical upgrades
- Plumbing upgrades
- Windows and doors
- Structural improvements
- Additions or major remodeling
The more substantial the planned work, the more important it is to establish a clear record of what existed when the property was purchased.
Why Does the Property’s Condition at Purchase Matter?
Suppose you buy a rental property with an older roof and replace it shortly after closing.
Years later, your CPA may need to determine:
- Whether the cost should have been capitalized
- When depreciation began
- Whether any existing property component was disposed of
- How the improvement affected basis
- What records support the tax treatment
That analysis becomes much easier if you documented the property when you bought it.
Useful records can include:
- Inspection reports
- Appraisal
- Photographs
- Contractor estimates
- Purchase agreement
- Repair negotiations
- Seller disclosures
- Closing documents
These records help establish what was part of the property at acquisition and what was added or replaced afterward.
What Should You Track for Every Major Renovation?
For each significant project, maintain records showing:
- What was replaced or improved
- Property address
- Contractor
- Description of work
- Cost
- Invoice date
- Payment date
- Completion date
- Date the improvement was placed in service
- Supporting contracts and receipts
Do not simply record a $40,000 renovation as one generic “repair expense.”
A project may contain several components with different tax treatments.
For example, a renovation might include:
- Painting
- New appliances
- Flooring
- Cabinets
- Plumbing repairs
- Electrical work
- Structural changes
Your accountant may need those costs broken out rather than receiving one lump-sum invoice.
Is a Roof Replacement a Repair or an Improvement?
A complete roof replacement will often raise different tax considerations than repairing a small damaged section.
Replacing an entire major building component may generally be treated as a capital improvement rather than a routine repair.
By contrast, fixing a localized leak or replacing a limited damaged portion may potentially receive different treatment depending on the facts.
The important point is that investors should not automatically classify every roof-related expense the same way.
What About HVAC Systems?
HVAC work can also range from ordinary maintenance to a significant capital expenditure.
Examples include:
Potential maintenance or repair
- Routine servicing
- Replacing a minor component
- Repairing a malfunction
Potential capital improvement
- Installing an entirely new HVAC system
- Replacing a major system
- Significantly upgrading the property’s heating or cooling infrastructure
The proper treatment depends on the nature and extent of the work.
How Should Kitchen and Bathroom Renovations Be Tracked?
Kitchen and bathroom projects often contain multiple components.
A kitchen renovation may include:
- Cabinets
- Countertops
- Appliances
- Flooring
- Plumbing
- Electrical work
- Painting
A bathroom renovation may include:
- Vanity
- Tile
- Plumbing fixtures
- Tub or shower
- Flooring
- Electrical
- Structural work
Keeping detailed contractor invoices can help your CPA determine which costs should be grouped together and whether any components receive separate depreciation treatment.
What About Flooring?
Flooring may receive different treatment depending on what was done and the type of property involved.
Replacing a small damaged area may differ from replacing flooring throughout the entire property.
The material can also matter. Carpet, tile, hardwood, and other flooring may not always receive identical tax treatment.
Track the specific cost, area replaced, material used, and completion date rather than categorizing everything simply as “flooring.”
How Should Appliances Be Recorded?
Appliances such as:
- Refrigerators
- Ranges
- Dishwashers
- Washers
- Dryers
may be depreciable assets separate from the building.
Keep receipts showing:
- Purchase price
- Delivery
- Installation
- Date placed in service
- Property where the appliance was installed
Do not automatically combine appliances with the building’s cost.
What About Landscaping?
Landscaping expenses can range from routine maintenance to larger improvements.
Examples may include:
Routine operating costs
- Lawn mowing
- Trimming
- Regular maintenance
Potential improvements
- Major landscaping redesign
- Irrigation installation
- Fencing
- Hardscaping
- Certain site improvements
The tax treatment depends on the nature of the expenditure, so detailed invoices matter.
How Should Furniture Be Tracked?
This is especially important for furnished rentals and short-term rentals.
Track items such as:
- Beds
- Sofas
- Tables
- Chairs
- Desks
- Outdoor furniture
- Other furnishings
Furniture may have different depreciation treatment from the building itself.
For a short-term rental, a meaningful portion of the total investment may consist of furniture, fixtures, and equipment, making accurate tracking especially important.
What About Structural Improvements?
Major structural work should be carefully documented.
Examples include:
- Room additions
- Wall removal
- Foundation work
- Structural reinforcement
- Garage conversion
- Major layout changes
These projects are generally more likely to involve capital expenditures than routine repairs.
They may also affect the property’s basis and depreciation schedule for many years.
What Is the Difference Between a Repair and a Capital Improvement?
At a high level:
A repair generally keeps the property in ordinary operating condition.
A capital improvement generally adds value, restores significant property, or adapts it to a new or different use.
The tax rules are more detailed than that simple distinction, and some expenditures require analysis under the tangible property regulations.
That is why investors should avoid using the size of the bill as the only test.
A $500 expense can potentially be capital in nature.
A larger expense may potentially qualify for current treatment under certain circumstances.
The facts matter.
Why Does the Placed-in-Service Date Matter for Improvements?
Capital improvements generally begin being depreciated when they are placed in service.
That may not be the same day:
- You sign the contract
- Pay a deposit
- Receive an invoice
- Begin construction
If a kitchen renovation starts in June but is not completed and available for rental use until August, the placed-in-service date may occur later than the payment date.
Document both the completion date and when the improvement became ready and available for its intended use.
Should Renovation Costs Be Included in the Property’s Basis?
Certain capital improvements generally increase adjusted basis.
That matters for:
- Depreciation
- Future gain calculations
- Property sales
- 1031 exchange planning
Routine repairs and operating expenses may receive different treatment.
The key is accurate classification from the beginning.
Why Should Renovation Planning Happen Before You Buy?
Pre-purchase planning helps answer questions such as:
- Is the property still financially attractive after needed improvements?
- Which costs are likely to be repairs versus capital improvements?
- How much cash will be required after closing?
- When will the property actually be ready to rent?
- When will depreciation begin?
- Could cost segregation be worth evaluating?
- How should the bookkeeping be set up?
- What records should be collected from contractors?
It also helps prevent a common mistake: buying a property, spending heavily on renovations, and then trying to reconstruct everything months later during tax preparation.
Before closing, create a renovation plan and begin a documentation file for the property.
At minimum, keep the property’s original condition, what was replaced, the cost of each project, invoices, payment records, completion dates, and placed-in-service dates.
That recordkeeping will make future decisions about repairs, capital improvements, depreciation, and adjusted basis much easier to support.
10. What Rental Property Expenses Should You Track From Day One?
From the moment you purchase a rental property, begin tracking expenses by specific category rather than putting everything into a general “rental expenses” account. Accurate categorization makes tax preparation easier, helps identify potential deductions, supports depreciation and basis calculations, and gives you a clearer picture of how the property is actually performing.
A good bookkeeping system should also allow you to see the income and expenses associated with each individual property.
Mortgage Interest
Track mortgage interest separately from mortgage principal.
Your monthly mortgage payment may include:
- Principal
- Interest
- Property taxes
- Insurance
- Escrow contributions
These components should not all be recorded as mortgage expense.
Mortgage principal generally reduces the loan balance rather than creating a current rental expense deduction. Interest associated with the rental property may generally be deductible subject to applicable tax rules and limitations.
Keep your year-end mortgage statements and loan documents so the interest reported in your books can be reconciled.
Property Taxes
Track property taxes separately from other expenses.
For Florida rental properties, maintain records of:
- Property tax bills
- Payments made directly
- Payments made through mortgage escrow
- Prorations from the year of purchase
- Special assessments
Do not assume every charge appearing on a property tax bill receives identical tax treatment. Certain assessments may require separate analysis.
Also be careful not to double count property taxes by recording both money deposited into escrow and the subsequent tax payment as expenses.
Insurance
Create a separate category for rental property insurance.
Depending on the property, this may include:
- Landlord insurance
- Property insurance
- Liability coverage
- Flood insurance
- Other rental-related coverage
Keep the policy, premium invoices, coverage period, and proof of payment.
If an insurance premium covers more than one tax year, your CPA may need to consider the applicable period when determining the proper treatment.
HOA and Condo Association Fees
If the property belongs to a homeowners or condominium association, track regular fees separately.
Also distinguish routine association dues from special assessments.
A normal monthly HOA payment may have different tax treatment from a special assessment used to fund a major capital project, such as a new roof, structural improvements, or other substantial work.
Keep notices explaining what special assessments are intended to fund rather than recording every association payment under the same expense category.
Repairs
Repairs should have their own bookkeeping category.
Examples may include:
- Fixing a plumbing leak
- Repairing a broken fixture
- Patching minor damage
- Repairing an appliance
- Minor electrical work
- Correcting ordinary wear and tear
Keep invoices that describe exactly what was repaired.
A credit card statement showing a $2,000 payment to a contractor does not explain whether the work involved an ordinary repair or a capital improvement.
Detailed invoices provide that context.
Maintenance
Maintenance should also be tracked separately from major improvements.
Examples may include:
- HVAC servicing
- Pool maintenance
- Lawn care
- Routine cleaning
- Pest control
- Pressure washing
- Gutter cleaning
- Routine property upkeep
Separating routine maintenance from repairs and capital improvements makes year-end classification considerably easier.
Property Management Fees
If you use a professional property manager, track:
- Monthly management fees
- Leasing fees
- Renewal fees
- Inspection fees
- Administrative charges
- Other management-related expenses
Keep the monthly property management statements.
Those statements can also help reconcile rental income, tenant charges, repair expenses, and distributions deposited into your bank account.
Do not simply record the net deposit from your property manager as rental income without reviewing the underlying statement.
For example, if the tenant pays $2,500 in rent and the manager retains $250 as a management fee before sending you $2,250, recording only $2,250 of rental income can understate both income and management expenses.
Utilities
Track landlord-paid utilities by category where practical.
These might include:
- Electricity
- Water
- Sewer
- Natural gas
- Trash service
- Internet provided to tenants
Utilities are particularly important for short-term rentals, where the owner commonly pays many expenses that long-term tenants might otherwise pay themselves.
If a tenant reimburses you for a utility or other expense, make sure the reimbursement is also accounted for correctly rather than simply reducing the expense without documentation.
Advertising and Leasing Expenses
Track expenses incurred to find tenants.
Examples may include:
- Rental listing fees
- Online advertising
- Professional photography
- Signs
- Leasing services
- Tenant screening
- Background checks
- Credit checks
These expenses can easily disappear into personal credit cards if the bookkeeping system is not established before the property is marketed.
Professional Fees
Create separate categories for professional services.
These can include:
- CPA fees
- Bookkeeping
- Tax advisory services
- Attorney fees
- Legal document preparation
- Property management consulting
- Other professional services related to the rental activity
Keep invoices describing the service performed because professional fees can receive different tax treatment depending on what the professional was hired to do.
For example, an attorney fee associated with acquiring a property may receive different treatment from a legal fee related to an existing tenant dispute.
Supplies
Track ordinary property-related supplies.
Depending on the rental, these might include:
- Cleaning supplies
- Light bulbs
- Filters
- Smoke detector batteries
- Small replacement items
- Tenant supplies
- Office supplies used to manage the property
Short-term rental investors may have substantially more recurring supply expenses, such as toiletries, linens, kitchen supplies, and guest amenities.
The fact that an individual purchase is small does not mean it should disappear from the bookkeeping records.
Transportation and Travel
Keep detailed records of eligible transportation and travel associated with managing the rental property.
Potential examples may include trips to:
- Inspect the property
- Meet contractors
- Purchase supplies
- Handle legitimate property-management activities
- Meet with professionals concerning the rental
However, not every trip connected in some way with real estate investing automatically creates a tax deduction.
Personal travel, commuting, and mixed business/personal trips require careful analysis.
For vehicle use, contemporaneous records should generally document information such as:
- Date
- Destination
- Business purpose
- Mileage
Do not wait until tax season and attempt to estimate an entire year’s mileage from memory.
Software and Technology
Modern real estate investors frequently use software to operate their portfolios.
Track expenses such as:
- Bookkeeping software
- Property management software
- Rent collection platforms
- Document storage
- Tenant screening platforms
- Scheduling tools
- Other software used for the rental activity
If a subscription is used for several properties, your bookkeeping system can allocate or track the expense appropriately rather than assigning it randomly to one property.
Don’t Forget Expenses Paid Personally
One of the easiest ways to miss legitimate rental property expenses is paying them from a personal account.
For example, an investor might use a personal credit card to buy:
- Hardware
- Cleaning supplies
- Replacement fixtures
- Software
- Contractor materials
If those transactions never enter the property’s books, they can easily be overlooked at tax time.
Ideally, use dedicated accounts for rental activity. When a legitimate rental expense is paid personally, provide the documentation to your bookkeeper so it can be recorded appropriately.
Track Expenses by Property
Once you own more than one rental, property-level accounting becomes especially important.
You should be able to determine:
Property A
- Rental income
- Operating expenses
- Repairs
- Management fees
- Net operating performance
Property B
- Rental income
- Operating expenses
- Repairs
- Management fees
- Net operating performance
Combining every rental into one large bucket makes it harder to evaluate profitability, prepare accurate records, analyze property-specific decisions, and identify potential problems.
Don’t Put Everything Under “Rental Expenses”
A bookkeeping report that shows:
Rental Expenses: $68,427
is far less useful than one showing:
- Mortgage interest: $17,400
- Property taxes: $7,200
- Insurance: $3,100
- HOA fees: $2,400
- Repairs: $5,800
- Maintenance: $3,600
- Property management: $7,500
- Utilities: $5,200
- Professional fees: $2,300
- Advertising: $900
- Supplies: $1,100
- Software: $600
- Other properly categorized expenses
Proper categorization gives your CPA enough information to evaluate the appropriate tax treatment and gives you much better information for managing the investment.
It also makes it easier to identify unusual expenses from year to year.
What Records Should You Keep for Rental Property Expenses?
For significant expenses, maintain supporting documentation such as:
- Receipts
- Contractor invoices
- Vendor invoices
- Credit card records
- Bank statements
- Property management statements
- Insurance documents
- Property tax bills
- HOA statements
- Mileage logs
- Travel records
- Software invoices
- Professional-service invoices
The bookkeeping entry tells you what was recorded.
The supporting documentation helps establish what the expense actually was and why it related to the rental property.
Why Should Expense Tracking Begin Immediately?
Waiting until tax season creates unnecessary problems.
By then, you may be trying to remember:
- Why you paid a contractor eight months ago
- Whether a Home Depot purchase was for the rental or your home
- Which property an expense belonged to
- Whether work was a repair or an improvement
- Why you traveled to another city
- Whether an HOA payment included a special assessment
A good system captures that information when the transaction occurs.
From day one, track mortgage interest, property taxes, insurance, HOA fees, repairs, maintenance, management fees, utilities, advertising, professional fees, supplies, eligible transportation and travel, software, and other property-specific costs in clearly defined categories.
Doing so doesn’t merely make tax preparation easier. It gives you the financial records needed to understand whether the rental property is actually performing the way you expected.
For a complete breakdown of deductible expenses and how different costs may be treated, see our upcoming Ultimate Guide to Rental Property Tax Deductions for Florida Real Estate Investors.
11. How Should You Set Up Your Bookkeeping Before Collecting the First Rent Payment?
Set up your rental property bookkeeping before the first rent payment arrives. Establishing separate accounts, a property-specific chart of accounts, and clear procedures for recording income, expenses, security deposits, mortgage payments, owner transactions, and fixed assets from the beginning can prevent months of cleanup later.
Good bookkeeping is not just about making tax preparation easier. It should allow you to answer a basic business question:
Is this rental property actually making money?
Should Your Rental Property Have a Separate Bank Account?
Using a dedicated bank account for rental activity makes it much easier to separate property transactions from personal spending.
Ideally, rental income flows into the dedicated account and property expenses are paid from it.
This creates a cleaner record of:
- Rent received
- Vendor payments
- Mortgage payments
- Property management expenses
- Repairs
- Utilities
- Insurance
- Owner contributions
- Owner distributions
If an LLC or other entity owns the property, maintaining separate financial activity can also be important for keeping the entity’s transactions distinct from the owner’s personal finances.
Avoid routinely depositing rent into your personal checking account and paying rental expenses from several unrelated personal accounts. Even when the underlying transactions are legitimate, mixing everything together makes bookkeeping and documentation considerably more difficult.
Should You Have a Separate Credit Card?
A dedicated credit card can also simplify recordkeeping, particularly if you frequently purchase:
- Repair materials
- Cleaning supplies
- Appliances
- Furniture
- Maintenance items
- Software
- Property-related supplies
A separate card is not a substitute for receipts and invoices, but it creates another clean transaction record.
If you use a personal credit card for a legitimate rental expense, make sure the transaction is entered into the rental property’s books rather than allowing the expense to disappear from the accounting system.
What Should Be Included in a Rental Property Chart of Accounts?
Your chart of accounts determines how transactions are categorized.
Avoid creating one account called:
Rental Expenses
Instead, establish categories that allow you and your CPA to understand what actually happened.
A basic rental property chart of accounts might include:
Income
- Rental income
- Late fees
- Other tenant income
- Other rental income
Operating Expenses
- Advertising
- Cleaning
- Insurance
- HOA/condo fees
- Legal fees
- Accounting and bookkeeping
- Property management
- Repairs
- Maintenance
- Landscaping
- Pest control
- Utilities
- Supplies
- Software
- Eligible transportation or travel
Assets
- Land
- Building
- Furniture
- Appliances
- Equipment
- Capital improvements
- Other fixed assets
Liabilities
- Mortgage payable
- Other loans
- Security deposit liabilities where applicable
- Credit card balances
Equity
- Owner contributions
- Owner distributions
The exact chart should reflect the property and ownership structure rather than using unnecessary accounts simply because they appear in generic accounting software.
How Should You Track Multiple Rental Properties?
Even if you own only one rental today, set up the bookkeeping with future growth in mind.
Once you acquire additional properties, your accounting system should allow you to see results for each property.
For example:
123 Main Street
- Income
- Operating expenses
- Repairs
- Net operating performance
456 Ocean Avenue
- Income
- Operating expenses
- Repairs
- Net operating performance
This can often be handled through classes, locations, properties, projects, tracking categories, or separate entity files depending on the accounting software and ownership structure.
The objective is simple: you should be able to determine how each property performs without manually sorting hundreds of transactions at year-end.
How Should Rental Income Be Recorded?
Record the gross rental income earned or received according to the accounting and tax method applicable to the activity.
Do not automatically record only the net amount deposited into your bank account.
Suppose a property manager collects:
Tenant rent: $2,500
and retains:
Management fee: $250
before depositing:
$2,250 into your account.
Simply recording $2,250 as rental income can understate both rental income and management expenses.
The books may instead need to reflect the underlying $2,500 of income and $250 management expense so the financial records accurately show what occurred.
Property management statements are therefore important bookkeeping documents.
How Should Security Deposits Be Recorded?
Security deposits should not automatically be treated as rental income.
If a deposit is refundable to the tenant under the rental agreement and applicable law, it may represent a liability rather than income when received.
Your bookkeeping system should therefore distinguish between:
- Rent
- Nonrefundable fees where applicable
- Refundable security deposits
- Security deposit deductions or amounts retained under applicable circumstances
Florida landlords should also comply with applicable state requirements governing the handling of tenant deposits.
Keeping deposits properly classified prevents rental income from being overstated.
How Should Mortgage Payments Be Recorded?
Do not record the entire mortgage payment as an expense.
A mortgage payment can include:
- Principal
- Interest
- Property taxes through escrow
- Insurance through escrow
Each component can have different accounting and tax treatment.
Principal generally reduces the mortgage liability.
Interest may generally be recorded as an interest expense subject to applicable tax rules.
Property taxes and insurance should be accounted for appropriately when paid rather than treating the entire mortgage payment as one expense.
Your year-end lender statements can help reconcile these amounts.
How Should Owner Contributions Be Recorded?
When you put personal money into the rental property, it generally should not be recorded as rental income.
For example, suppose you transfer $20,000 from your personal savings account into the rental bank account to fund renovations.
That transfer is not $20,000 of rent.
Depending on the ownership structure, it may represent an owner contribution, capital contribution, loan, or another form of funding.
The correct treatment depends on the entity and circumstances.
Recording owner funding separately prevents artificial inflation of the property’s operating income.
How Should Owner Distributions Be Recorded?
Similarly, money you transfer from the rental property to yourself generally should not automatically be recorded as a property operating expense.
If the rental account has $15,000 of excess cash and you transfer $5,000 to your personal account, that does not mean the property incurred a $5,000 deductible expense.
Depending on the ownership structure, the transfer may represent an owner draw, distribution, or another equity transaction.
This distinction is critical because:
Cash leaving the bank account does not automatically equal a tax deduction.
How Should Capital Improvements Be Recorded?
Capital improvements should be tracked separately from routine repairs and maintenance.
Examples may include:
- New roof
- Major HVAC replacement
- Kitchen renovation
- Bathroom renovation
- Building addition
- Significant structural work
- Other qualifying improvements
Instead of automatically recording these amounts as repair expenses, your accounting system should allow them to be reviewed and capitalized when required.
Keep:
- Contractor invoices
- Contracts
- Receipts
- Payment records
- Description of work
- Completion date
- Placed-in-service date
This information allows your CPA to determine the appropriate depreciation treatment.
What Are Fixed Assets?
Fixed assets are longer-term assets used in the rental activity rather than ordinary recurring operating expenses.
Depending on the property, these may include:
- Building
- Furniture
- Appliances
- Equipment
- Certain improvements
- Other depreciable property
These items should generally be tracked separately so they can be added to the appropriate depreciation schedules.
For example, buying a $1,500 appliance is different from paying a $1,500 utility bill.
Both involve $1,500 leaving your bank account, but their tax and accounting treatment may be very different.
Should You Connect Your Bank Accounts to QuickBooks or Other Accounting Software?
Bank feeds can make bookkeeping more efficient, but automation does not eliminate the need for proper categorization.
Accounting software may import a transaction from a hardware store, for example, but it cannot always determine whether that purchase represented:
- Routine supplies
- A repair
- A capital improvement
- An appliance
- A personal purchase
The investor or bookkeeper still needs enough information to classify the transaction correctly.
Save supporting documentation rather than assuming the bank-feed description will be sufficient years later.
How Often Should Rental Property Books Be Updated?
Monthly bookkeeping is generally far easier than reconstructing an entire year at tax time.
Each month, review:
- Bank reconciliations
- Credit card reconciliations
- Rental income
- Property management statements
- Mortgage activity
- Repairs
- Capital purchases
- Owner contributions
- Owner distributions
- Security deposits
- Outstanding bills
Regular reviews also help identify duplicate transactions, missing expenses, incorrect categories, and unusual property costs while the transactions are still fresh.
What Reports Should a Rental Property Investor Review?
At minimum, your accounting system should allow you to review:
Profit and Loss Statement
Shows rental income and operating expenses over a particular period.
Balance Sheet
Shows assets, liabilities, and equity.
Property-Level Profit and Loss
For investors with multiple properties, this helps identify which rentals are performing well and which require attention.
These reports become increasingly valuable as your portfolio grows.
Why Should You Set Everything Up Before the First Rent Payment?
Bookkeeping becomes harder to fix as transactions accumulate.
If you wait six months, you may have to reconstruct:
- Which expenses belonged to the rental
- Which expenses were personal
- What contractor work involved
- Whether an expenditure was a repair or improvement
- Which deposits were rent
- Which deposits were owner contributions
- Which payments were security deposits
- How mortgage payments should have been divided
- Which property each transaction belonged to
Setting up the system before collecting the first rent payment avoids much of that cleanup.
Start with a dedicated bank account, an appropriate chart of accounts, property-level tracking, and clear procedures for rental income, security deposits, mortgage payments, owner contributions and distributions, capital improvements, and fixed assets.
The result is more than cleaner tax records. You gain reliable financial information that can help you evaluate cash flow, profitability, future acquisitions, and the overall performance of your real estate portfolio.
For a complete bookkeeping framework, see Real Estate Investor Bookkeeping: How to Set Up Your Books for Maximum Tax Savings.
12. How Should Security Deposits Be Recorded?
A refundable security deposit generally should not automatically be recorded as rental income when a landlord receives it. If the tenant is entitled to receive the deposit back at the end of the lease, subject to applicable deductions, the landlord is generally holding money that may need to be returned rather than receiving ordinary rental income.
That distinction should be reflected in the property’s bookkeeping from the beginning.
What Is the Difference Between Rent and a Security Deposit?
Rental income is generally money paid by a tenant for the right to occupy or use the property.
Examples may include:
- Monthly rent
- Additional rent required under the lease
- Certain nonrefundable fees
- Other payments that represent income to the landlord
A refundable security deposit serves a different purpose.
The landlord generally holds the deposit during the tenancy and may be required to return it when the lease ends, assuming the tenant satisfies the lease terms and there are no amounts the landlord is legally permitted to retain.
Because the landlord may have an obligation to return that money, a refundable security deposit generally should not simply be categorized as rental income when received.
How Should a Refundable Security Deposit Be Recorded?
From a bookkeeping perspective, a refundable tenant security deposit will generally be tracked as a liability rather than ordinary rental income.
For example, suppose a new tenant pays:
- First month’s rent: $2,500
- Refundable security deposit: $2,500
The books should not necessarily show $5,000 of rental income.
Instead, the accounting may reflect:
Rental income: $2,500
Security deposit liability: $2,500
The $2,500 security deposit represents an amount that may eventually need to be returned to the tenant.
This allows the property’s financial statements to distinguish actual operating income from money being held on behalf of a tenant.
What If the Security Deposit Is Used as the Last Month’s Rent?
The terms of the payment matter.
If money received in advance is intended to cover the tenant’s final month’s rent rather than being refundable as a security deposit, its tax treatment may differ.
Investors should not assume that every amount collected at move-in is a security deposit simply because it is collected alongside one.
The lease and the purpose of the payment should clearly distinguish among:
- Current rent
- Advance rent
- Refundable security deposits
- Other tenant payments
Your CPA can determine the appropriate tax treatment based on the agreement and applicable tax rules.
What Happens If You Return the Security Deposit?
If the tenant fulfills the lease obligations and the refundable deposit is returned, the bookkeeping should generally remove the corresponding liability.
For example:
Security deposit received: liability increases.
Security deposit returned: liability decreases.
The original receipt and subsequent refund generally should not artificially increase rental income and rental expenses when the money was simply being held temporarily for the tenant.
What If You Keep Part of the Security Deposit?
The treatment can change when a landlord becomes entitled to retain some or all of a security deposit.
Suppose a landlord holds a $2,500 refundable security deposit and, under the lease and applicable law, retains $600 for qualifying tenant-caused damage while returning $1,900.
The accounting should reflect what actually occurred rather than leaving the entire $2,500 recorded as a liability.
Depending on the circumstances and applicable tax rules, an amount the landlord becomes entitled to retain may need to be recognized as income.
The corresponding repair or other property expenditure should be accounted for separately based on its actual tax treatment.
Do not simply net everything together without documentation.
What If the Deposit Is Retained for Unpaid Rent?
If an amount from a security deposit is properly applied to unpaid rent, that amount may generally become rental income when the landlord becomes entitled to retain it.
Again, the important distinction is between:
Money temporarily held with an obligation to potentially return it
and
Money the landlord has become entitled to keep.
The bookkeeping should reflect when that change occurs.
Why Should Security Deposits Have Their Own Account?
Creating a dedicated security deposit liability account makes the books easier to understand and reconcile.
For each property, you should be able to determine:
- Which tenant paid the deposit
- Amount received
- Date received
- Amount currently being held
- Any amounts properly applied or retained
- Amount refunded
- Date refunded
For investors with several rental properties, tenant-level records become even more important.
At any point, the total security deposit liability in the accounting system should be supportable by records showing the deposits being held for individual tenants.
What Happens When You Buy an Occupied Rental Property?
Security deposits become especially important when purchasing a property that already has tenants.
As part of the transaction, the seller may transfer responsibility for existing tenant deposits to the buyer.
The closing documents should identify any applicable security deposit amounts and related credits or transfers.
Those amounts should not automatically be treated as new rental income simply because the buyer receives funds or a closing credit associated with the deposits.
Instead, the new owner may also be assuming an obligation related to those tenant deposits.
This is another reason your CPA should review the closing statement when you purchase an occupied rental property.
What Florida Rules Apply to Security Deposits?
Florida landlords also need to comply with applicable state landlord-tenant requirements concerning security deposits and advance rent.
Those requirements can address issues such as:
- How deposits are held
- Required notices
- Interest in certain circumstances
- Returning deposits
- Procedures for making claims against deposits
- Applicable deadlines
These legal requirements are separate from the accounting and federal tax treatment discussed here.
Rental property owners should make sure their deposit procedures comply with current Florida law and consult a qualified Florida attorney when legal guidance is needed.
What Records Should You Keep for Security Deposits?
Maintain documentation including:
- Signed lease
- Deposit amount
- Date received
- Proof of payment
- Bank records
- Required tenant notices
- Move-in inspection documentation
- Move-out inspection documentation
- Correspondence concerning deductions
- Repair documentation
- Amount retained, if any
- Amount returned
- Date returned
Good records help support both the bookkeeping treatment and the landlord’s handling of the deposit.
Why Does Correct Security Deposit Accounting Matter?
Recording every tenant payment as rent can overstate rental income and distort the property’s financial performance.
It can also make it difficult to determine how much money is actually owed back to tenants.
Your accounting system should clearly distinguish among:
Rental income — money earned from renting the property
Refundable security deposits — money being held that may need to be returned
Amounts properly retained — money the landlord becomes entitled to keep under the lease and applicable law
Setting up these categories before the first tenant moves in gives you cleaner financial statements, more accurate tax records, and a much easier way to track your obligations to tenants.
13. Will Your Rental Property Losses Be Tax Deductible?
A rental property can show a tax loss without giving you an immediate deduction against your salary or other nonpassive income. Federal passive activity rules can limit when rental losses are deductible, so creating a tax deduction and being allowed to use the resulting loss immediately are two different questions.
This distinction is especially important for new investors who expect depreciation and rental expenses to automatically reduce the taxes they pay on W-2 income.
Does a $15,000 Rental Property Loss Reduce Your Salary by $15,000?
Not necessarily.
Suppose your rental property generates:
- $30,000 of rental income
- $25,000 of operating expenses
- $20,000 of depreciation
The property would show a simplified tax loss of:
$15,000
A new investor might assume:
“I made $100,000 at my job, so now I’ll only be taxed as though I made $85,000.”
That is not automatically how the rules work.
Rental real estate activities are generally treated as passive activities for federal income tax purposes, even when an investor spends meaningful time managing the property, unless an applicable exception applies.
The passive activity rules determine whether that $15,000 loss can currently offset other income.
What Are the Passive Activity Loss Rules?
The passive activity rules generally separate income and losses into categories.
At a high level, income may include:
- Passive income
- Nonpassive business income
- W-2 wages
- Portfolio income
- Other categories subject to their respective rules
Passive losses generally can offset passive income, subject to applicable rules.
But passive losses generally cannot automatically be used to offset nonpassive income such as wages.
For example, an investor who has a $15,000 passive rental loss and $20,000 of passive income from another activity may have a different result from an investor who has the same $15,000 rental loss but only W-2 wages.
This is why the amount shown as a loss on the rental property’s profit-and-loss statement does not, by itself, tell you how much of a tax deduction you can currently use.
What Is Active Participation in Rental Real Estate?
There is a special federal tax rule that may allow certain taxpayers who actively participate in rental real estate to deduct up to a specified amount of rental real estate losses against nonpassive income, subject to income limitations and other requirements.
Active participation is generally a less demanding standard than material participation.
Activities that may support active participation can include meaningful management decisions such as:
- Approving tenants
- Setting rental terms
- Approving expenditures
- Making other significant management decisions
However, the special allowance is subject to adjusted gross income phaseouts and other requirements.
Investors should therefore avoid assuming that owning and managing one rental automatically means all losses are deductible against wages.
Your CPA should calculate whether the special allowance applies to your circumstances.
What Is Material Participation?
Material participation is a separate concept.
The tax rules contain several tests used to determine whether a taxpayer materially participates in an activity.
The analysis can consider factors such as:
- Number of hours spent participating
- Whether participation was substantially all of the activity
- Participation relative to other individuals
- Participation over multiple years
- Facts and circumstances
Simply owning the property is not enough.
Investors who need to establish material participation should maintain contemporaneous records of the work they perform rather than attempting to estimate their participation months later.
Does Material Participation Automatically Make a Long-Term Rental Nonpassive?
Not necessarily.
This is an important distinction.
Rental activities are generally treated as passive regardless of whether the taxpayer materially participates, unless an exception applies.
One important exception involves taxpayers who qualify as real estate professionals under the federal tax rules and materially participate in their rental activities.
That means an investor generally cannot simply say:
“I materially participate in my rental, so my rental loss is automatically nonpassive.”
The Real Estate Professional Status rules may also need to be satisfied for traditional rental real estate.
What Is Real Estate Professional Status?
Real Estate Professional Status, often shortened to REPS, can significantly affect the treatment of rental real estate losses.
To qualify, a taxpayer must satisfy specific federal requirements involving the amount of time spent in real property trades or businesses and the relationship between those activities and the taxpayer’s other work.
Qualification alone is not enough.
The investor must also address material participation in the rental activities for the losses to potentially receive nonpassive treatment.
This is why REPS planning involves two related questions:
- Do you qualify as a real estate professional?
and
- Did you materially participate in the relevant rental activity or activities?
Both can matter.
Can Real Estate Professional Status Allow Rental Losses to Offset W-2 Income?
Potentially, when the applicable requirements are satisfied.
If an investor qualifies as a real estate professional and materially participates in the applicable rental activity, the rental activity may be treated as nonpassive.
That can potentially allow qualifying rental losses to offset other nonpassive income.
However, this should never be treated as an automatic “W-2 tax loophole.”
The taxpayer must actually satisfy the requirements, and documentation can be critical.
Other tax limitations may also affect the ultimate deduction.
What Happens If You Cannot Deduct the Rental Loss This Year?
A passive loss that cannot currently be used is generally suspended rather than simply disappearing.
Suspended passive losses can generally be carried forward to future tax years.
They may potentially become usable when:
- The activity generates passive income
- Other passive activities generate income
- The taxpayer’s circumstances change
- The property or activity is disposed of in a qualifying fully taxable transaction
- Other applicable requirements are satisfied
This means a suspended loss can still have future tax value.
Your tax records should therefore track these losses from year to year.
What Are Suspended Passive Losses?
Suppose your rental generates a $15,000 passive loss and none of it is currently deductible because of the passive activity rules.
That $15,000 does not necessarily vanish.
Instead, it may become a suspended passive loss carried into future years.
The following year, if the rental or another passive activity generates sufficient passive income, some or all of the suspended loss may potentially become deductible, subject to the applicable rules.
This is why investors should know not only:
“How much did my rental lose this year?”
but also:
“How much suspended passive loss am I carrying forward?”
That number can become important when planning future income, property sales, and portfolio decisions.
What Happens to Suspended Losses When You Sell the Property?
A fully taxable disposition of your entire interest in a passive activity to an unrelated party can generally allow previously suspended passive losses associated with that activity to be released, subject to the applicable rules.
This makes suspended losses an important part of sale planning.
Before selling a rental property, ask your CPA:
- How many suspended losses are associated with this property?
- How will the sale affect those losses?
- What gain will the property generate?
- How does depreciation affect the sale?
- Is a 1031 exchange being considered?
- How would an exchange affect the overall tax strategy?
Do not evaluate a sale based solely on appreciation or expected cash proceeds.
What If You Own Several Rental Properties?
The analysis can become more complicated as the portfolio grows.
One property might generate:
$20,000 passive income
while another generates:
$15,000 passive loss.
Depending on the circumstances, passive income and losses across activities can interact.
Investors may also need to consider how rental activities are treated separately or grouped under applicable tax rules.
This is another reason property-level bookkeeping is important. Your CPA needs to know what each property generated before determining how the tax rules apply across the portfolio.
Why Should You Think About Passive Losses Before Buying?
Before purchasing your first rental, ask your CPA to model more than cash flow.
You may see an investment projection showing:
- Positive cash flow
- Depreciation
- Large paper loss
- Estimated “tax savings”
But those projected tax savings may assume that you can immediately use the loss.
That assumption needs to be tested.
Ask:
- Will this rental likely be a passive activity for me?
- Could I qualify for the special rental real estate loss allowance?
- Do income limitations affect me?
- Could Real Estate Professional Status realistically apply?
- Will I materially participate?
- Do I have other passive income?
- If losses are suspended, when might I be able to use them?
A tax strategy based on a deduction you cannot currently use may produce very different results from the investment projection you were shown.
What Records Should You Keep?
If participation may affect the tax treatment of your rental activity, maintain records throughout the year.
Depending on your circumstances, documentation may include:
- Date of activity
- Time spent
- Property involved
- Description of work
- Property management activities
- Tenant-related activities
- Contractor meetings
- Property inspections
- Bookkeeping or administrative work when applicable
- Other qualifying participation
The quality and relevance of the records matter.
Waiting until tax season and creating an estimated annual total from memory is much weaker than maintaining contemporaneous documentation.
What Should First-Time Investors Remember?
The key concept is:
A rental property tax loss and an immediately usable tax deduction are not necessarily the same thing.
Depreciation, repairs, operating expenses, cost segregation, and other strategies may legitimately create or increase a rental property loss.
But whether that loss can reduce your current taxes depends on another layer of rules, including:
- Passive activity limitations
- Active participation
- Income limitations
- Material participation
- Real Estate Professional Status
- Other passive activities
- Suspended loss carryforwards
Before purchasing a property based partly on projected tax savings, have your CPA determine whether those projected deductions are likely to be currently usable in your specific tax situation.
For a detailed explanation of the requirements that can affect whether qualifying rental losses are treated as passive or nonpassive, see How to Qualify for Real Estate Professional Status and Protect Your Deductions in Florida.
14. Could Real Estate Professional Status Matter to You?
Real Estate Professional Status (REPS) may be important if you expect your rental properties to generate tax losses and want to determine whether those losses can potentially offset nonpassive income. However, qualifying requires meeting specific federal requirements, and investors should evaluate their eligibility before relying on REPS as part of a tax strategy.
Who Should Investigate Real Estate Professional Status?
REPS is particularly worth discussing with your CPA if you:
- Own or plan to own multiple rental properties
- Spend substantial time managing real estate
- Work in a real property trade or business
- Expect significant depreciation deductions
- Are considering cost segregation
- Expect your rentals to generate tax losses
- Have substantial nonpassive income
- Have a spouse who spends significant time managing the rental portfolio
The potential benefit can become more significant as an investor’s portfolio and depreciation deductions grow.
However, generating a large rental loss does not itself make someone a real estate professional.
Why Does Your Employment or Other Business Activity Matter?
The federal requirements for Real Estate Professional Status consider both the amount of time spent in qualifying real property trades or businesses and how that time compares with the taxpayer’s other personal services during the year.
That means your overall work situation matters.
Someone who works full-time outside real estate may face a very different REPS analysis from someone whose primary working activity involves managing, developing, brokering, constructing, or operating real estate.
Before assuming you will qualify, tell your CPA about:
- W-2 employment
- Self-employment
- Other businesses
- Real estate activities
- Hours devoted to each activity
REPS should be evaluated based on what you actually do during the year, not simply on the fact that you own rental properties.
Does Qualifying as a Real Estate Professional Automatically Make Rental Losses Deductible?
No.
This is one of the most important points for investors to understand.
Qualifying as a real estate professional is only part of the analysis. You generally must also materially participate in the applicable rental activity or activities for those activities to potentially be treated as nonpassive.
Material participation is determined under separate tests that evaluate the taxpayer’s involvement in the activity.
Depending on the circumstances, investors with multiple rentals may also need to consider how their activities are treated for purposes of applying these rules.
This is why REPS planning should involve both:
Real Estate Professional Status
and
Material Participation
rather than treating them as interchangeable concepts.
Why Should You Track Your Time?
If you expect to rely on REPS or material participation, contemporaneous documentation is extremely important.
Your records may include:
- Date
- Property
- Activity performed
- Time spent
- Purpose of the activity
Relevant activities might include qualifying property management, tenant matters, contractor oversight, property inspections, leasing activities, and other work directly connected with operating the real estate activity, depending on the applicable rules.
Not every hour related in some way to real estate necessarily counts.
Your CPA can help you understand which activities are relevant to the applicable tests.
Can Your Spouse’s Real Estate Activity Matter?
Yes, but the rules need to be applied carefully.
For married investors, a spouse’s participation can be relevant to certain material participation determinations. However, the requirements for qualifying as a real estate professional contain specific rules that should not be confused with the material participation rules.
Do not simply combine every hour worked by both spouses and assume the result establishes REPS.
If one spouse has a demanding full-time job while the other manages the rental portfolio, for example, that fact pattern may warrant specific planning with a tax professional.
When Should You Start Keeping REPS Records?
During the year—not after it ends.
If you purchase your first rental property in April and believe Real Estate Professional Status or material participation could become relevant, begin documenting your activities in April.
Do not wait until the following March and try to reconstruct hundreds of hours from memory.
Contemporaneous records are more useful because they can show:
- What you did
- When you did it
- Which property was involved
- How long the activity took
Calendar entries, property management records, emails, invoices, and other documentation can also help support your records, depending on the circumstances.
Why Should First-Time Investors Think About REPS Before Buying?
You do not need to qualify for Real Estate Professional Status to invest successfully in rental property.
But if your projected tax strategy depends heavily on using rental losses against other income, you should understand whether those losses are actually likely to be usable.
Before buying, ask your CPA:
- Will my rental activity generally be passive?
- Could Real Estate Professional Status realistically apply to me?
- What requirements would I need to satisfy?
- How does material participation affect the analysis?
- What activities should I document?
- Could my spouse’s participation matter?
- What happens if my rental losses are passive and suspended?
Answering these questions before the year unfolds is much better than discovering during tax preparation that the large rental loss you expected to use is subject to passive activity limitations.
For a complete explanation of the qualification requirements, material participation, documentation, and common mistakes, see How to Qualify for Real Estate Professional Status and Protect Your Deductions in Florida.
15. Are You Buying a Short-Term Rental or Long-Term Rental?
Whether you plan to operate a property as a traditional long-term rental or a short-term rental through platforms such as Airbnb or VRBO can significantly change the tax and operating analysis. The length of guest stays, services provided, personal use, material participation, furnishings, expenses, and local tax requirements can all affect how the investment should be planned.
Before purchasing the property, decide how you realistically expect to operate it rather than assuming every rental property receives identical tax treatment.
| Issue | Long-Term Rental | Short-Term Rental |
| Typical tenant/guest use | Longer | Shorter |
| Operating intensity | Lower | Often higher |
| Personal use considerations | Possible | Often important |
| Material participation | Relevant | Potentially very important |
| Furnishings | Less extensive | Often significant |
| Cleaning/turnover | Lower | Frequent |
| Local compliance | Relevant | Often more extensive |
Why Can Short-Term Rentals Receive Different Tax Treatment?
For federal tax purposes, the label you use for the property does not necessarily determine how the activity is treated.
Calling a property an “Airbnb” does not automatically place it into one tax category, just as calling another property a “rental” does not answer every passive activity question.
Factors such as the average period of customer use and the level of services provided can affect how the activity is analyzed under the passive activity rules.
This distinction can become particularly important when the property generates a tax loss.
Traditional rental real estate is generally treated as passive, subject to applicable exceptions. Certain short-term rental activities may be analyzed differently under the passive activity rules when they do not meet the applicable definition of a rental activity.
That can make material participation especially important.
Why Does Material Participation Matter for Short-Term Rentals?
For certain short-term rental activities, an investor who materially participates may potentially receive different passive or nonpassive treatment than an investor in a traditional long-term rental.
This is one reason short-term rentals are frequently discussed as a tax-planning strategy.
But investors should be careful with simplified claims such as:
“Buy an Airbnb and deduct the loss against your salary.”
The actual analysis depends on the facts and applicable tax rules.
Your CPA may need to consider:
- Average guest stay
- Services provided
- Your participation
- Hours worked
- Participation by other individuals
- Property management arrangements
- Personal use
- Depreciation
- Other passive activities
A large depreciation deduction does not automatically mean the resulting loss can be used against wages.
How Does Using a Property Manager Affect the Analysis?
Short-term rental investors frequently hire property managers to handle:
- Guest communication
- Reservations
- Cleaning coordination
- Pricing
- Maintenance
- Check-in and checkout
- Marketing
Using a property manager does not automatically determine the tax result, but it can be relevant when evaluating the owner’s level of participation.
If your tax strategy depends on materially participating in the activity, understand what work you will actually perform before outsourcing most of the operation.
Document your participation throughout the year rather than attempting to recreate it at tax time.
Why Are Furnishings More Important for Short-Term Rentals?
A traditional long-term rental may be leased with relatively little personal property.
A short-term rental, on the other hand, may require:
- Beds
- Sofas
- Tables
- Chairs
- Televisions
- Kitchen equipment
- Linens
- Outdoor furniture
- Appliances
- Décor
- Other guest amenities
These purchases can represent a significant portion of the investor’s initial cash outlay.
They should be tracked separately from the building because furniture, appliances, equipment, and other qualifying assets may receive different depreciation treatment.
Keep detailed purchase records showing:
- Item
- Cost
- Purchase date
- Property
- Date placed in service
Do not simply categorize the entire cost of furnishing an Airbnb as “setup expenses.”
How Do Cleaning and Turnover Expenses Differ?
A long-term rental may have relatively infrequent tenant turnover.
Short-term rentals can require cleaning after virtually every guest stay.
That can create recurring expenses for:
- Cleaning services
- Laundry
- Linens
- Toiletries
- Paper products
- Guest supplies
- Restocking
- Maintenance
- Pool or spa service
- Landscaping
These expenses should be tracked from the beginning.
Short-term rental investors should build a chart of accounts that reflects the actual operating model rather than using bookkeeping categories designed solely for traditional long-term rentals.
What If You Plan to Use the Property Personally?
Personal use is particularly important for vacation-oriented short-term rentals.
An investor might purchase a Florida beach property intending to rent it most of the year while also using it personally for several weeks.
Those personal-use days can affect the property’s tax treatment and how certain expenses and losses are handled.
Keep records showing:
- Rental days
- Personal-use days
- Days spent performing qualifying work where relevant
- Dates the property was available for rent
- Dates the property was unavailable
Do not assume that simply listing the property on Airbnb converts all costs associated with the property into deductible rental expenses.
What About Depreciation and Cost Segregation?
Short-term rental properties often contain substantial furniture, equipment, and other components in addition to the building itself.
That can make depreciation planning especially important.
Depending on the property and investor, the analysis may include:
- Building depreciation
- Furniture and equipment
- Appliances
- Improvements
- Cost segregation
- Bonus depreciation when applicable
- Placed-in-service dates
Cost segregation can potentially accelerate depreciation on qualifying components, but—as discussed earlier—the resulting tax loss is only one part of the analysis.
You must also determine whether and when that loss can actually be used.
Are Florida Short-Term Rentals Subject to Additional Taxes?
Potentially.
Short-term rental operators in Florida may need to consider taxes and compliance requirements beyond federal income taxes.
Depending on the property’s location and how it is operated, these can include:
- Florida sales and use tax requirements
- Tourist development or other local transient-rental taxes
- Registration requirements
- Local licensing
- Business tax receipts
- Zoning or land-use restrictions
- Condominium or HOA restrictions
Some booking platforms may collect and remit certain taxes in particular circumstances, but investors should not assume the platform handles every state and local obligation applicable to the property.
Verify the requirements for the specific county and municipality before purchasing.
Why Should Local Rules Be Checked Before Closing?
A property can look excellent on a spreadsheet but fail as a short-term rental investment if local rules prevent or materially restrict the intended use.
Before buying, investigate:
- Whether short-term rentals are permitted
- Minimum stay requirements
- Licensing
- Occupancy limits
- Parking requirements
- Safety requirements
- Local taxes
- HOA or condominium restrictions
This is both an investment and compliance issue.
Your tax strategy should be based on how the property can legally and realistically operate, not simply on projected Airbnb revenue.
Which Strategy Is Better for Tax Purposes?
There is no universal answer.
A short-term rental can present planning opportunities that differ from a traditional long-term rental, but it can also require substantially more management, documentation, furnishings, turnover expenses, and regulatory compliance.
A long-term rental may offer simpler operations but can be subject to different passive activity considerations.
The appropriate choice should primarily be driven by whether the property is a sound investment and fits your goals—not by chasing a tax result.
Before purchasing, model both:
Investment economics
and
Tax consequences.
Ask your CPA to evaluate how your expected rental model affects depreciation, passive activity rules, material participation, deductible expenses, and your overall tax position.
For a detailed discussion of these issues, see Short-Term Rental Tax Strategies for Florida Airbnb and VRBO Investors.
16. Are You Planning to Use the Property Personally?
If you expect to use the rental property yourself, let family members stay there, or eventually convert it into a residence, that should be part of the tax planning before you buy. Personal use can affect how expenses are allocated, whether losses are deductible, how the activity is classified, and the property’s overall tax treatment.
This is especially important for vacation homes and short-term rentals, where investors may be tempted to mix investment and personal use.
What Counts as Personal Use?
Personal use can include situations such as:
- You stay at the property for vacation.
- Your family uses the property.
- Friends or relatives stay there for less than fair market rent.
- You reserve the property for personal use during peak season.
- You eventually convert the property into a primary or secondary residence.
The exact tax treatment depends on the facts, but investors should not assume that a property remains a pure rental simply because it is listed on Airbnb or VRBO.
Why Should You Track Personal-Use Days?
Personal-use days should be documented from the beginning because they can affect how rental expenses and losses are treated.
Keep records showing:
- Days rented at fair market value
- Days used personally
- Days used by family or friends
- Days the property was available for rent
- Days spent performing qualifying maintenance or management activities
- Periods when the property was unavailable
These records can become important when your CPA determines how the property should be treated for tax purposes.
How Can Personal Use Affect Expense Deductions?
When a property has both rental and personal use, some expenses may need to be allocated between the rental portion and the personal portion.
That can affect deductions for items such as:
- Mortgage interest
- Property taxes
- Insurance
- Utilities
- Repairs
- Maintenance
- HOA fees
- Depreciation
The allocation method depends on the applicable tax rules and the property’s actual use.
This means that a $12,000 annual expense does not necessarily produce a $12,000 rental deduction if the property is used personally for part of the year.
Can Personal Use Limit Rental Losses?
Potentially.
Mixed-use or vacation-home rules can limit the extent to which rental expenses create a deductible loss.
For certain properties, the amount of personal use relative to rental use can affect whether the property is treated under rules that restrict deductions.
That is why investors should not rely on a projected tax loss without first considering how much personal use is expected.
If the property is intended primarily as an investment, extensive personal use can change the tax analysis.
What If Family Members Use the Property?
Family use can matter, particularly if the property is provided below fair market rent.
For example, letting a family member stay in the property for free or at a heavily discounted rate may not be treated the same way as renting it to an unrelated tenant at market rates.
Investors should document:
- Who used the property
- Dates of use
- Amount charged
- Comparable market rent
- Whether the stay was personal or rental use
Do not assume that receiving some payment automatically converts every family stay into qualifying rental use.
What If the Property Is Rented Seasonally?
Seasonal rentals often create mixed-use situations.
For example, an investor might:
- Rent the property from January through April
- Use it personally during the summer
- Rent it again during the holidays
In that situation, expenses may need to be allocated based on the applicable rental and personal-use rules.
Seasonal investors should maintain a calendar showing exactly how the property was used throughout the year.
What If You Eventually Convert the Rental Into Your Residence?
Some investors buy a property as a rental with the intention of eventually living in it.
That can create important tax consequences later.
The property may have:
- Prior depreciation
- Adjusted basis
- Rental-period expenses
- Personal-use periods
- Appreciation
A future sale may therefore involve different tax consequences than the sale of a home that was always used solely as a primary residence.
If conversion to personal use is part of the long-term plan, discuss that strategy with your CPA before making the change.
Can Personal Use Affect Depreciation?
Yes.
Depreciation generally applies to the rental or business use of property, not the personal-use portion.
If the property is used for both rental and personal purposes, depreciation may need to be limited or allocated accordingly.
Personal use can also affect how certain losses are treated.
This is another reason accurate day-by-day records can be valuable.
Why Does This Matter More for Short-Term Rentals?
Short-term rentals often blur the line between investment and personal use.
An owner might rent the property most of the year but reserve several weeks for personal vacations.
Because short-term rentals can also involve material participation, significant depreciation, and cost segregation, personal-use days can become part of a much larger tax analysis.
Investors should not treat personal stays as an afterthought.
What Should You Decide Before Buying?
Before purchasing a property you may use personally, ask:
- How many days per year do I expect to use it?
- Will family members use it?
- Will I charge fair market rent?
- Will it be a seasonal rental?
- Will I eventually convert it to a residence?
- How will personal use affect deductions?
- Could personal use limit losses?
- How should I track rental and personal days?
A property can be both a good investment and a place you occasionally enjoy personally, but the tax treatment may become more complex.
The key is to plan for that mixed use before buying and track personal-use days from the beginning so your CPA can properly determine expense allocation, loss limitations, rental classification, depreciation, and other tax consequences.
17. What Florida-Specific Taxes and Costs Should Rental Property Investors Consider?
Florida does not impose an individual state income tax, but that does not mean owning rental property in Florida is free from state and local tax obligations. Investors may need to account for property taxes, short-term rental taxes, sales and use tax requirements, licensing, entity fees, and other costs that vary by property type and location.
Before buying, determine which requirements apply to the specific property, rental model, county, municipality, and ownership structure.
How Do Florida Property Taxes Affect Rental Property Investors?
Florida rental property owners generally need to budget for annual property taxes imposed at the local level.
The amount can depend on factors such as:
- Assessed value
- Taxable value
- Local millage rates
- Applicable assessments
- Property location
- Ownership and use
A new investor should be particularly careful about relying on the seller’s current property tax bill when projecting future expenses.
A property’s tax situation can change after a sale, so the seller’s historical property tax amount may not necessarily represent what the new owner will pay going forward.
When analyzing a potential rental property, build your projections using a reasonable estimate of your expected property taxes after acquisition, not simply the amount shown on the seller’s most recent bill.
Does Florida’s Homestead Exemption Apply to Rental Property?
Florida’s homestead rules are generally associated with qualifying permanent residences, not properties held strictly as investments.
A property purchased and operated solely as a rental generally should not be assumed to qualify for the same homestead-related benefits that may apply to an owner’s permanent Florida residence.
This can matter when investors compare:
- Their own home’s property tax bill
- The seller’s property tax bill
- The expected taxes on a newly purchased rental
Investors planning to convert a residence into a rental—or eventually convert a rental into their residence—should evaluate how that change in use could affect property taxes and other tax considerations.
Homestead issues can involve both tax and legal questions, so property-specific guidance may be appropriate.
Are Florida Short-Term Rentals Subject to Sales Tax?
Short-term accommodations can create Florida sales and use tax obligations that generally do not apply in the same way to traditional long-term residential leases.
Depending on the length and nature of the rental, an investor operating through platforms such as Airbnb or VRBO may need to consider Florida taxes applicable to transient accommodations.
Do not assume that because the property is “residential real estate,” all rental income is treated identically.
The rental period and how the property is operated can matter.
What Are Tourist Development Taxes?
Florida counties may impose local tourist development taxes on qualifying short-term accommodations.
These taxes are separate from other taxes that may apply to the rental.
The rules and rates can vary by county, which means a short-term rental in one part of Florida may have different local tax obligations from a similar property somewhere else in the state.
Depending on the jurisdiction and booking method, taxes may be:
- Collected by the owner
- Collected by a property manager
- Collected and remitted by a booking platform
- Subject to separate registration or filing requirements
Investors should verify exactly who is responsible for collecting, reporting, and remitting each applicable tax.
Do not assume Airbnb, VRBO, or another platform handles every obligation associated with your property.
Why Does the Property’s County and City Matter?
Florida rental rules are not uniform statewide.
A property can potentially be subject to requirements imposed by:
- State of Florida
- County
- Municipality
- Condominium association
- Homeowners association
Depending on the location and rental model, local requirements may address:
- Business tax receipts
- Rental registrations
- Vacation rental licenses
- Occupancy
- Parking
- Safety requirements
- Inspections
- Noise
- Minimum rental periods
- Local taxes
This is particularly important for short-term rentals.
Two properties located only a few miles apart can potentially fall within different jurisdictions and have different operating requirements.
What Licensing Requirements Should You Investigate?
Before purchasing a property intended for rental use, determine whether the planned activity requires state or local registrations, licenses, or permits.
Depending on the circumstances, investors may need to investigate requirements involving:
- Florida vacation rental licensing
- Local vacation rental registration
- Business tax receipts
- County registration
- City registration
- Sales tax registration
- Tourist development tax registration
- Other property-specific permits
The requirements can depend on the rental model and location.
Do this research before closing, especially when projected investment returns depend on operating the property as a short-term rental.
Why Should Short-Term Rental Investors Verify Platform Tax Collection?
Booking platforms can make tax compliance easier by collecting certain taxes from guests and remitting them in some jurisdictions.
However, platform collection should not be treated as proof that every obligation has been satisfied.
An investor should determine:
- Which taxes apply to the property?
- Which taxes does the platform collect?
- Which taxes does the platform remit?
- Which taxes remain the owner’s responsibility?
- Are tax returns still required even when the platform remits the tax?
- Does direct booking create additional collection responsibilities?
This becomes particularly important if you accept reservations through multiple platforms or directly through your own website.
What Florida Costs Should an LLC Owner Budget For?
If you create a Florida LLC to own the rental property, the entity itself can create additional costs.
Depending on the structure, these may include:
- Formation fees
- Annual report fees
- Registered agent costs
- Accounting costs
- Tax preparation costs
- Legal costs
- Bookkeeping
- Separate banking
- Other administrative expenses
A multi-member LLC or an entity that makes additional tax elections may also require more complex federal tax reporting.
This is why an LLC should not be evaluated only by asking:
“Does it provide liability protection?”
Investors should also consider the ongoing administrative and financial cost of maintaining the structure.
Are There Additional Costs for Out-of-State Investors?
An investor does not need to live in Florida to own Florida rental property.
However, an out-of-state investor may need to consider obligations in more than one jurisdiction.
That can include:
- Florida property-related requirements
- Federal income taxes
- Tax rules in the investor’s home state
- Entity registration
- Multi-state tax reporting
- Local rental compliance
The absence of a Florida individual income tax does not necessarily mean an out-of-state investor has no state income tax consequences elsewhere.
Your CPA should consider the investor’s state of residence as part of the overall tax analysis.
What Should You Verify Before Buying a Florida Rental Property?
Before closing, create a property-specific compliance checklist.
Verify:
- Estimated property taxes after purchase
- Whether homestead-related treatment currently affects the property
- Intended rental use
- Florida sales and use tax requirements
- Applicable tourist development taxes
- County requirements
- Municipal requirements
- Short-term rental restrictions
- Required registrations
- Required licenses
- HOA or condominium restrictions
- Entity formation and annual costs
- Tax collection responsibilities
- Booking platform responsibilities
For a long-term rental, many short-term accommodation requirements may not apply.
For an Airbnb or other transient rental, the list can be considerably longer.
The key is not to assume that every Florida rental property has the same tax and compliance obligations.
A long-term rental in Stuart, a vacation rental in Miami Beach, and a condo rented seasonally in Orlando can face very different local requirements even though all three properties are located in Florida.
Evaluate the specific property and intended use before purchasing so state and local taxes, licensing requirements, and administrative costs are included in your investment projections rather than discovered after closing.
18. Should You Think About the Exit Strategy Before You Buy?
Yes. Before purchasing a rental property, ask yourself: How do I eventually expect to exit this investment? You may sell the property, hold it for decades, refinance it, complete a 1031 exchange, convert it to personal use, or transfer it as part of an estate plan. Today’s ownership and tax decisions can affect tomorrow’s options.
You do not need to know exactly what will happen 10 or 20 years from now. But thinking about likely exit scenarios before purchasing can help you avoid creating an ownership or tax structure that becomes difficult or expensive to change later.
What Are the Most Common Exit Strategies for Rental Property Investors?
Your eventual strategy might include:
- Selling the property outright
- Holding the property long term
- Refinancing and continuing to hold
- Exchanging into another investment property
- Converting the property to personal use
- Bringing in or buying out partners
- Transferring property to family members
- Incorporating the property into an estate plan
- Leaving property to heirs
- Completing a 1031 exchange into a different type of investment real estate
Each path can create different tax considerations.
That is why the question should not only be:
“How should I buy this property?”
It should also be:
“Will the way I buy this property today support what I may want to do with it later?”
What Happens If You Eventually Sell the Property?
Selling a rental property can create a taxable gain.
At a simplified level, the tax calculation considers factors such as:
- Sales proceeds
- Selling expenses
- Adjusted tax basis
- Capital improvements
- Depreciation
- Applicable depreciation-related tax consequences
This is why accurate basis and depreciation records are so important from the first year of ownership.
Suppose you buy a property for $400,000 and sell it many years later for $700,000.
The taxable result is not necessarily calculated by simply subtracting $400,000 from $700,000.
Your adjusted basis may have changed because of:
- Depreciation
- Capital improvements
- Acquisition costs
- Other applicable adjustments
Tax planning at acquisition helps establish the records needed to calculate the eventual sale correctly.
How Does Depreciation Affect Your Exit?
Depreciation can provide valuable deductions while you own rental property, but investors should understand that depreciation can also affect the tax consequences of a future sale.
Depreciation generally reduces adjusted basis over time.
That means an investor who receives substantial depreciation deductions during ownership should not assume those deductions have no effect when the property is sold.
This does not mean investors should avoid depreciation.
Instead, depreciation should be viewed as part of the property’s entire investment lifecycle:
Acquisition → Operation → Depreciation → Sale or Exchange
Tax planning should consider all four stages.
What If You Plan to Hold the Property Long Term?
A long-term investor may prioritize different considerations from someone planning to sell within three years.
If your intention is to hold for decades, planning may involve:
- Long-term depreciation
- Capital improvement tracking
- Refinancing
- Portfolio expansion
- Estate planning
- Ownership succession
- Future transfers
- Potential exchanges
A long holding period also makes accurate records increasingly important.
Twenty years from now, you may need documentation showing what you paid for the property, what improvements were made, and how depreciation was calculated.
Do not rely on being able to reconstruct those records later.
What If You Refinance Instead of Selling?
Some investors build wealth by holding appreciated properties and refinancing rather than selling them.
A refinance can allow an investor to access equity without completing a traditional sale.
Borrowed funds generally are not automatically taxable income merely because the investor receives cash, since the loan creates an obligation to repay the lender.
However, refinancing creates other considerations, including:
- New financing costs
- Interest expense
- Use of loan proceeds
- Debt levels
- Cash flow
- Future acquisition plans
How the proceeds are used can also affect the tax treatment of related interest.
If refinancing is part of your long-term strategy, consider financing flexibility when deciding how the property should initially be owned.
What If You Want to Exchange the Property for Another Investment?
A Section 1031 exchange may allow an investor to defer recognition of eligible gain when qualifying investment or business real property is exchanged for other qualifying real property and the applicable requirements are satisfied.
This can allow investors to move from one property into another without immediately recognizing all of the eligible gain that would otherwise arise from an outright taxable sale.
For example, an investor might eventually exchange:
- Single-family rental → multifamily property
- Small rental → larger investment property
- One geographic market → another market
- Management-intensive property → different investment real estate
The ability to exchange can become an important part of long-term portfolio growth.
For a detailed explanation, see 1031 Exchange Guide for Florida Real Estate Investors.
Why Does a 1031 Exchange Require Advance Planning?
A 1031 exchange generally cannot be treated as an afterthought once the investor has completed a conventional sale and received the proceeds.
Deferred exchanges involve strict requirements and deadlines, commonly including:
- Proper transaction structure
- Use of a qualified intermediary
- Identification of replacement property
- Completion of the replacement-property acquisition within the applicable period
If a 1031 exchange might be part of your exit, involve your CPA and qualified exchange professionals before the sale closes.
The same planning principle applies at acquisition: understanding that an exchange could be part of your future strategy can influence how you maintain basis, ownership, and property records throughout the investment period.
What If You Eventually Convert the Rental Into a Residence?
Some investors purchase properties that they may eventually occupy personally.
For example, you might buy:
- A Florida vacation rental you plan to retire in
- A property near the coast you expect to occupy later
- A rental near family that could eventually become your residence
Converting a rental property to personal use does not erase its rental history.
The property may already have:
- Depreciation deductions
- Adjusted basis
- Capital improvements
- Rental periods
- Personal-use periods
- Significant appreciation
Those factors can affect the tax consequences of an eventual sale.
If future conversion is part of your plan, tell your CPA before changing the property’s use.
What If You Want to Transfer the Property to Family?
Rental properties are often held long enough to become part of family wealth planning.
An investor may eventually consider:
- Gifting an interest
- Adding family members as owners
- Transferring property to an entity
- Leaving the property to heirs
- Incorporating the property into a broader estate plan
These decisions can involve income tax, gift tax, estate tax, basis, legal, and asset-protection considerations.
Do not transfer appreciated real estate casually simply because changing the name on an entity or deed appears easy.
Coordinate significant ownership transfers with both tax and legal professionals.
How Can Estate Planning Affect the Way You Buy Today?
If your goal is to hold rental property for life and eventually transfer it to heirs, estate planning can become part of the ownership decision.
Relevant considerations may include:
- How title is held
- Entity ownership
- Multiple owners
- Succession
- Estate documents
- Basis consequences
- Management after death
- Family ownership goals
The appropriate structure depends heavily on the investor’s circumstances, so estate planning should involve a qualified estate-planning attorney along with tax professionals.
The important point for a first-time investor is simply to recognize that a rental property can become a long-term family asset, not merely a source of current rental income.
Why Can Entity Structure Affect Your Exit?
The entity that owns the property can influence what happens when you later:
- Sell
- Add a partner
- Remove a partner
- Transfer ownership
- Distribute property
- Reorganize your portfolio
- Plan your estate
This is one reason choosing an entity solely for a perceived first-year tax benefit can be shortsighted.
For example, as discussed earlier, holding appreciating real estate in an S corporation can create different considerations if the investor later wants to distribute the property out of the corporation.
The ownership structure should therefore be evaluated based on both entry and exit.
What If Your Strategy Changes?
It probably will.
A first-time investor might initially plan to hold one rental forever and then, five years later, decide to:
- Sell it
- Exchange into a multifamily property
- Add a partner
- Move into it
- Refinance
- Build a larger portfolio
- Transfer assets to family
Tax planning cannot predict every future decision.
The goal is to avoid unnecessarily restricting your future options.
Flexible structures, accurate records, proper bookkeeping, and proactive tax planning make it easier to respond when the investment strategy changes.
What Should You Ask Before Buying?
Before closing on your first rental property, ask:
- How long do I expect to own this property?
- Am I buying primarily for cash flow, appreciation, or both?
- Could I eventually sell it outright?
- Could I use a 1031 exchange?
- Might I refinance instead of selling?
- Could I eventually live in the property?
- Might I add another investor?
- Could I transfer the property to family?
- Is this intended to become part of my estate?
- Does my proposed ownership structure give me reasonable flexibility?
You do not need perfect answers.
You simply need to recognize that the purchase is the first step in a much longer tax and investment lifecycle.
The strongest real estate tax strategies consider how you enter the investment, how you operate it, and how you eventually leave it.
Today’s entity structure, basis records, depreciation strategy, bookkeeping, and ownership decisions can affect a sale, refinance, conversion, family transfer, estate plan, or 1031 exchange years later.
For investors considering an exchange as part of that future strategy, see 1031 Exchange Guide for Florida Real Estate Investors.
19. Could You Eventually Use a 1031 Exchange?
A 1031 exchange can potentially allow a real estate investor to defer recognition of eligible gain when qualifying real property held for investment or business use is exchanged for other qualifying real property. You do not need to know when buying your first rental whether you will eventually complete an exchange, but you should understand the option before building your long-term strategy.
What Does a 1031 Exchange Actually Do?
Section 1031 of the Internal Revenue Code allows qualifying exchanges of real property held for investment or productive use in a trade or business.
When the requirements are satisfied, an investor may be able to defer recognition of eligible gain that otherwise could be recognized when selling the property.
The word defer is important.
A 1031 exchange generally does not permanently erase taxable gain. Instead, the tax basis of the replacement property is determined under the applicable exchange rules, allowing eligible gain to be carried forward rather than necessarily recognized immediately.
That makes a 1031 exchange primarily a tax-deferral strategy, not an automatic method for eliminating taxes.
What Type of Property Can Qualify?
Section 1031 currently applies to qualifying real property held for investment or productive use in a trade or business.
For a real estate investor, that can potentially include different types of investment real estate.
An investor might, for example, exchange:
- One rental property for another rental property
- A single-family investment property for multifamily real estate
- One commercial property for another qualifying property
- Investment real estate in Florida for qualifying investment real estate in another state
The replacement property does not necessarily need to look exactly like the property being sold.
However, personal-use property and property primarily held for sale can raise different issues, so investors should confirm eligibility before assuming a transaction qualifies.
What Is Replacement Property?
The property you dispose of in an exchange is commonly referred to as the relinquished property.
The qualifying real estate you acquire is the replacement property.
For example, an investor might sell a Florida rental that has appreciated substantially and use a properly structured 1031 exchange to acquire a larger investment property.
This can potentially allow the investor to reposition the portfolio while deferring eligible gain.
Investors commonly use exchanges as part of strategies to:
- Move into larger properties
- Consolidate several investments
- Change geographic markets
- Change property types
- Reduce management responsibilities
- Reposition a real estate portfolio
Why Is a Qualified Intermediary Important?
In a typical deferred 1031 exchange, investors generally cannot simply sell the property, take control of the proceeds, and later decide to use those funds for an exchange.
A qualified intermediary is commonly engaged before the sale closes to facilitate the exchange and hold the proceeds according to the applicable requirements.
This is why 1031 planning must happen before the investor completes a conventional sale.
If you are considering an exchange, contact your CPA and a qualified intermediary before closing on the relinquished property.
Waiting until the sale proceeds have already been received can be too late to restructure the completed sale into a qualifying deferred exchange.
What Are the 1031 Exchange Timing Requirements?
Deferred 1031 exchanges have strict deadlines.
Generally, an investor must identify potential replacement property within 45 days after transferring the relinquished property.
The replacement property generally must then be received by the earlier of:
- 180 days after transferring the relinquished property, or
- The due date, including extensions, of the applicable tax return for the year in which the transfer occurred.
These periods run concurrently.
That means the 180-day period does not begin after the 45-day identification period ends.
Missing an applicable deadline can cause the exchange to fail, which is why investors should begin searching for potential replacement properties and assembling their professional team before the original property closes.
Do You Have to Reinvest All of the Sale Proceeds?
An investor does not necessarily have to reinvest every dollar for a transaction to involve a 1031 exchange, but receiving cash or other nonqualifying property can result in some gain being recognized.
Debt and replacement-property value can also affect the tax result.
Because these calculations can become complex, investors should not rely on a simple rule such as:
“Just buy another property for the same price.”
Have your CPA model the proposed transaction before closing so you understand how much gain may be deferred and whether any portion may remain taxable.
Why Should First-Time Investors Understand 1031 Exchanges Now?
You may have no intention of selling your first rental property anytime soon.
That’s fine.
The purpose of learning about 1031 exchanges before purchasing is not to commit yourself to using one.
It is to understand that your future exit strategy may include more options than simply:
Sell property → Pay applicable tax → Keep remaining cash
A future exchange could potentially allow you to move from one investment property into another while deferring eligible gain.
Knowing that possibility exists can influence how you:
- Maintain basis records
- Track depreciation
- Document improvements
- Structure ownership
- Plan future acquisitions
- Evaluate property sales
- Build your portfolio
Why Does Recordkeeping Matter for a Future Exchange?
If you hold the property for many years before exchanging it, your CPA may need accurate records showing:
- Original purchase price
- Acquisition costs
- Land/building allocation
- Capital improvements
- Depreciation claimed
- Adjusted basis
- Prior exchanges, if any
Poor records can make the tax analysis substantially more difficult.
A first-time investor may not think those documents will matter 15 years later, but they can become essential when the property has appreciated and a sale or exchange is being considered.
When Should You Start Planning the Actual Exchange?
Before you sell.
Once you seriously consider disposing of the property, involve your professional team early.
That may include:
- CPA
- Qualified intermediary
- Real estate attorney
- Real estate agent or broker
- Financial advisor, where appropriate
Your CPA can evaluate the tax consequences of selling versus exchanging, while the qualified intermediary can help structure and facilitate the exchange.
Do not wait until after closing to ask whether the completed sale can become a 1031 exchange.
Should Every Appreciated Rental Property Be Exchanged?
No.
A 1031 exchange can be valuable, but it is not automatically the best strategy for every sale.
An investor may prefer an outright sale because:
- Cash is needed for another purpose
- No suitable replacement property is available
- The investor wants to leave real estate
- The expected tax liability is manageable
- The replacement investment does not make economic sense
- Other tax considerations change the analysis
Avoid purchasing a poor replacement property simply to defer taxes.
The investment should make financial sense independently of the tax strategy.
What Should You Remember Before Buying Your First Rental?
You do not need to decide today whether your first rental property will eventually be part of a 1031 exchange.
But you should understand the option.
Your future strategy could look like:
Buy → Operate → Improve → Appreciate → Exchange → Acquire Larger Property
rather than:
Buy → Operate → Sell → Exit
Understanding both possibilities makes it easier to establish accurate basis records, maintain depreciation schedules, preserve transaction documents, and think strategically about how the first property could fit into a much larger real estate portfolio.
If a 1031 exchange eventually becomes part of your exit strategy, begin planning before the property is sold.
For a complete explanation of eligibility, deadlines, replacement-property rules, qualified intermediaries, and common mistakes, see our 1031 Exchange Guide for Florida Real Estate Investors.
20. What Should You Ask Your CPA Before Closing?
Before closing on your first rental property, meet with your CPA while there is still time to make informed decisions. The conversation should cover much more than whether the property will generate a tax deduction. Ownership, basis, depreciation, bookkeeping, passive losses, property use, and your eventual exit strategy should all be considered.
Use the following checklist to guide that conversation.
First Rental Property CPA Checklist
☐ How should I own the property?
Ask whether purchasing individually, through a single-member LLC, multi-member LLC, partnership, or another structure makes sense for your situation. Tax considerations should be coordinated with an attorney’s advice regarding liability and legal ownership.
☐ What will my federal tax classification be?
An LLC’s legal structure and federal tax classification are not necessarily the same. Understand whether the entity will be treated as a disregarded entity, partnership, corporation, or another classification for federal tax purposes.
☐ How should the purchase price be allocated?
Determine how the acquisition price and applicable costs should be allocated among land, building, and any other acquired assets. This allocation can directly affect future depreciation.
☐ What will my depreciable basis be?
The property’s purchase price is not automatically its depreciable basis. Land generally is not depreciable, and certain acquisition costs and adjustments may affect the calculation.
☐ When will depreciation begin?
Ask when the property will be considered placed in service. Closing on the property does not necessarily mean depreciation begins immediately if significant renovations are required before it is ready and available for rent.
☐ Should I consider cost segregation?
Ask whether the property’s value, components, expected holding period, and your tax position make a cost segregation study worth evaluating. Cost segregation can accelerate depreciation, but it is not automatically appropriate for every rental property.
☐ How should planned renovations be treated?
Discuss renovations you expect to complete immediately after purchase. Determine how repairs, maintenance, capital improvements, furniture, appliances, and other assets should be documented and tracked.
☐ What expenses should I track from day one?
Establish categories for mortgage interest, property taxes, insurance, HOA fees, repairs, maintenance, property management, utilities, advertising, professional fees, supplies, software, and eligible transportation or travel.
☐ How should I set up my bookkeeping?
Ask about separate bank accounts, credit cards, the chart of accounts, property-level tracking, security deposits, mortgage payments, owner contributions and distributions, capital improvements, and fixed assets.
☐ Could passive loss limitations affect me?
Do not assume that a projected rental tax loss will automatically offset salary or other nonpassive income. Ask whether the passive activity rules could limit your ability to use losses currently.
☐ Could Real Estate Professional Status apply to me?
If you spend substantial time in real estate or expect significant rental losses, discuss whether Real Estate Professional Status warrants consideration and what documentation you should maintain throughout the year.
☐ Does short-term versus long-term rental use change my strategy?
Tell your CPA exactly how you plan to operate the property. Average guest stays, services, material participation, furnishings, depreciation, personal use, and local tax requirements can make short-term rental planning different from traditional long-term rental planning.
☐ How does personal use affect the tax treatment?
If you or family members expect to use the property, discuss how personal-use days could affect expense allocation, depreciation, rental losses, and other tax treatment.
☐ What Florida taxes might apply?
Ask about property taxes and, where relevant, Florida sales and use tax, tourist development taxes, and other state or local obligations associated with your intended rental model.
☐ What documents should I save from closing?
Identify the records your CPA will need, including the purchase agreement, closing statement, loan documents, appraisal, property tax information, insurance documents, entity records, and invoices associated with the acquisition.
☐ What should I consider before eventually selling the property?
Discuss adjusted basis, depreciation, capital improvements, potential taxable gain, passive loss carryforwards, and whether a future 1031 exchange could fit your long-term investment strategy.
Don’t Wait Until Tax Season to Ask These Questions
The purpose of a pre-closing CPA meeting is not to predict every tax issue you will encounter during the life of the property. It is to identify decisions that are easier to make before the transaction occurs.
After closing, your CPA can calculate depreciation, prepare tax returns, and report what happened. But some choices involving ownership, financing, documentation, renovations, and transaction structure may be harder or more expensive to change later.
Bring this checklist to your CPA before signing the final closing documents. The goal is to enter your first rental property investment with the ownership structure, tax records, bookkeeping system, and long-term strategy established correctly from the beginning.
21. What Documents Should You Save When Buying Your First Rental Property?
Keep a complete acquisition file from the day you purchase your first rental property. Documents from the purchase may remain important for decades because they can help establish tax basis, support depreciation, document capital improvements, substantiate expenses, and calculate taxable gain or loss when you eventually sell or exchange the property.
Do not assume your lender, title company, real estate agent, or CPA will always have copies available years later.
First Rental Property Document Checklist
Keep copies of the following:
☐ Purchase Contract
Save the final signed purchase agreement along with material amendments or addenda. The contract documents the terms under which you acquired the property and may provide information relevant to the property’s purchase price, included assets, credits, and other aspects of the transaction.
☐ Closing or Settlement Statement
This is one of the most important documents in your acquisition file. It can show the purchase price, financing, property tax prorations, title charges, recording fees, credits, escrow amounts, and other acquisition-related costs your CPA may need to classify properly.
☐ Loan Documents
Keep the promissory note, mortgage, closing disclosure, and other financing documents. These records can help establish the original loan balance, interest terms, points, origination costs, and other financing expenses that may need to be tracked over time.
☐ Appraisal
Keep any appraisal prepared for the purchase or financing. It may contain information about the property’s land, building, improvements, condition, comparable properties, and valuation that can be useful when evaluating the allocation between land and depreciable property.
☐ Property Inspection Report
The inspection provides a record of the property’s condition when you acquired it. This can become useful when documenting what existed at purchase and distinguishing subsequent repairs, replacements, renovations, and capital improvements.
☐ Property Tax Information
Keep property tax bills, assessment information, and relevant records from the county property appraiser. These documents can help with tax payments, property-level bookkeeping, and evaluation of land and improvement values.
☐ Insurance Documents
Maintain the original landlord, property, liability, flood, and other applicable insurance policies along with premium records. Keep replacement policies as coverage changes over time.
☐ Entity Documents
If an LLC, partnership, or other entity owns the property, keep applicable documents such as formation records, operating agreements, ownership records, tax elections, and other governing documents.
These records can become particularly important if you later add or remove owners.
☐ Improvement Invoices
Keep detailed invoices for renovations and capital improvements made after purchase.
Examples may include:
- Roof replacement
- HVAC systems
- Kitchen renovations
- Bathroom renovations
- Flooring
- Windows
- Plumbing
- Electrical work
- Structural improvements
- Additions
These records can affect depreciation and adjusted basis.
☐ Contractor Invoices
Contractor documentation should explain what work was actually performed.
A credit card statement showing a $15,000 payment to a contractor tells your CPA very little about whether the expenditure was a repair, improvement, appliance purchase, or combination of several items.
Ask contractors for detailed invoices and keep them with the property records.
☐ Furniture and Equipment Receipts
If you purchase furniture, appliances, or equipment for the rental, maintain individual purchase records.
Examples include:
- Refrigerators
- Ranges
- Dishwashers
- Washers and dryers
- Beds
- Sofas
- Tables
- Televisions
- Outdoor furniture
- Property equipment
These assets may receive different depreciation treatment from the building itself.
☐ Legal Invoices
Keep invoices from attorneys associated with the acquisition, entity formation, contracts, title matters, and other property-related legal services.
The nature of the legal service can affect its tax treatment, so retain the detailed invoice rather than recording only the amount paid.
☐ Accounting and Tax Advisory Invoices
Maintain records of CPA, bookkeeping, tax planning, and accounting services related to the property.
Again, the purpose of the service matters. An accounting fee related to establishing the acquisition may potentially receive different treatment from recurring bookkeeping or tax preparation services.
What Additional Records Are Worth Keeping?
Depending on the transaction, your permanent property file may also include:
- Title insurance policy
- Survey
- Deed
- Seller disclosures
- HOA or condominium documents
- Existing leases
- Security deposit records
- Property management agreements
- Permits
- Contractor agreements
- Before-and-after photographs
- Cost segregation study
- Depreciation schedules
- Records of major repairs
- Refinancing documents
As the property changes over time, continue adding important records to the same file.
Why Should You Keep Records of the Property’s Original Condition?
Documenting the property’s condition at acquisition can help establish what existed before you began making changes.
For example, if you replace a roof six months after purchasing the property, your original:
- Inspection
- Appraisal
- Photographs
- Contractor estimates
may help document the roof’s condition when you acquired it.
The same applies to kitchens, bathrooms, HVAC systems, flooring, appliances, and other property components.
This creates a much clearer history of the investment.
Why Are Improvement Records So Important?
Capital improvements can increase the property’s adjusted tax basis and may also be depreciated under applicable rules.
Suppose you hold a rental for 15 years and during that period spend:
- $30,000 on a roof
- $45,000 renovating the kitchen
- $18,000 on HVAC
- $25,000 renovating bathrooms
- $12,000 on other qualifying improvements
Those expenditures could become important when calculating depreciation and the property’s adjusted basis.
If the documentation is missing when you eventually sell, reconstructing 15 years of improvements can be extremely difficult.
How Long Should You Keep Rental Property Acquisition Records?
Some property records may need to be retained much longer than ordinary annual receipts.
Documents establishing the property’s basis and subsequent adjustments can remain relevant for as long as you own the property and potentially beyond the year in which you dispose of it, subject to applicable record-retention requirements.
That includes records supporting:
- Original cost
- Acquisition costs
- Land/building allocation
- Capital improvements
- Depreciation
- Adjusted basis
Do not automatically discard these records simply because several tax returns have already been filed.
Why Do These Records Matter When You Sell?
When you eventually sell the property, your CPA may need to determine its adjusted tax basis.
That calculation can depend on records dating all the way back to the original acquisition.
At a simplified level, the analysis may involve:
Original Basis
+ Qualifying Capital Improvements
− Applicable Depreciation and Other Adjustments
= Adjusted Basis
The adjusted basis is then relevant when calculating the tax consequences of the sale.
Missing acquisition or improvement records can make that calculation much harder.
Why Do These Records Matter for a 1031 Exchange?
If you eventually complete a 1031 exchange, accurate basis and depreciation records become especially important.
A qualifying exchange generally defers eligible gain rather than simply erasing the property’s tax history.
As investors move from one property into another, accurate records can become increasingly important for tracking basis through the investment lifecycle.
A document from your first rental purchase may therefore still matter years later when you exchange that property into a much larger investment.
Should You Keep Digital Copies?
Yes. Maintaining organized digital copies can protect against lost or damaged paper records.
Consider creating a permanent folder for each property:
123 Main Street
→ Acquisition
→ Financing
→ Taxes
→ Insurance
→ Leases
→ Repairs
→ Capital Improvements
→ Furniture & Equipment
→ Legal
→ Accounting
→ Depreciation
→ Refinancing
→ Sale/1031 Exchange
Use clear filenames that include dates and descriptions.
For example:
2026-06-15_Roof-Replacement_ABC-Roofing_$28,500.pdf
is considerably more useful years later than:
IMG_4837.pdf
What Should You Send Your CPA Immediately After Closing?
At minimum, send:
- Purchase contract
- Final closing/settlement statement
- Loan documents
- Appraisal when available
- Property tax information
- Relevant insurance information
- Entity documents
- Information about renovations beginning after closing
Then continue providing records for major improvements, refinancing, ownership changes, and other significant transactions.
Your acquisition file should follow the property for its entire investment lifecycle.
A receipt or closing document that seems unimportant today may become critical years later when your CPA needs to establish basis, depreciation, capital improvements, or taxable gain on a sale or 1031 exchange.
22. What Should You Do Immediately After Closing?
The first 30 days after buying a rental property are the best time to establish accurate tax and accounting records. Save your closing documents, record the acquisition correctly, establish property-level bookkeeping, document renovations and the placed-in-service date, and begin tracking depreciation and participation before details become difficult to reconstruct.
First 30 Days After Buying the Property
1. Save All Closing Documents
Create a permanent acquisition file immediately.
Save:
- Purchase agreement
- Final closing or settlement statement
- Loan documents
- Deed and title documents
- Appraisal
- Inspection report
- Property tax information
- Insurance documents
- HOA or condominium documents
- Entity documents
- Existing leases and security deposit information, if applicable
These documents may remain relevant throughout the entire period you own the property and when you eventually sell or exchange it.
2. Finalize Your Bookkeeping System
Do not wait until the first tax return is due to establish the books.
Make sure your accounting system is ready to record:
- Rental income
- Mortgage interest
- Property taxes
- Insurance
- HOA fees
- Repairs
- Maintenance
- Property management
- Utilities
- Professional fees
- Supplies
- Capital improvements
- Fixed assets
- Owner contributions
- Owner distributions
The earlier the system is established, the less cleanup will be required later.
3. Establish Property-Specific Accounts and Tracking
Use a dedicated bank account for rental activity where appropriate and consider a separate credit card for property expenses.
If you expect to own multiple rentals, establish property-level tracking from the beginning.
Your accounting system should eventually allow you to answer:
How much income did this property generate?
How much did this property cost to operate?
How profitable is this specific investment?
Do not wait until you own five properties to begin separating them.
4. Record the Acquisition Correctly
Provide your CPA or bookkeeper with the closing documents so the purchase can be entered correctly.
The accounting may need to distinguish among:
- Land
- Building
- Other acquired assets
- Mortgage debt
- Owner contribution
- Acquisition costs
- Financing costs
- Escrow
- Property tax adjustments
- Insurance
- Credits and prorations
Avoid recording only the cash you brought to closing as the property’s purchase cost.
The accounting records should reflect the complete transaction.
5. Document the Land and Building Allocation
Establish a supportable allocation between land and depreciable property.
Land generally is not depreciated, while the building generally is.
Keep supporting information such as:
- Appraisal
- County property appraiser information
- Purchase documents
- Other relevant valuation evidence
Your CPA can use the available information to determine an appropriate approach based on the facts and circumstances.
Do not arbitrarily assign a nominal amount to land simply to increase depreciation deductions.
6. Track Renovations Separately
If work begins immediately after closing, create a renovation file before the first contractor invoice arrives.
Track each project separately:
- Roof
- HVAC
- Kitchen
- Bathrooms
- Flooring
- Appliances
- Furniture
- Electrical
- Plumbing
- Landscaping
- Structural improvements
Keep:
- Contracts
- Invoices
- Receipts
- Payment records
- Before-and-after photographs
- Completion dates
- Placed-in-service dates
Do not combine a $50,000 renovation into one generic bookkeeping category called “repairs.”
Your CPA may need to distinguish repairs, capital improvements, furniture, equipment, and other property components.
7. Document the Placed-in-Service Date
The closing date and depreciation start date are not necessarily the same.
Document when the property became ready and available for its intended rental use.
If you purchase a turnkey rental and immediately make it available to tenants, the placed-in-service date may occur shortly after closing.
If you purchase a property requiring several months of substantial renovations, the placed-in-service date may occur later.
Keep evidence such as:
- Rental listings
- Contractor completion records
- Property management agreements
- Photographs
- Leasing correspondence
- Tenant applications
- Lease documents
Do not rely on remembering the date years later.
8. Begin Tracking Income and Expenses
Start recording transactions as soon as the property begins generating activity.
Track expenses in specific categories rather than putting everything under “rental expenses.”
At minimum, monitor:
- Rental income
- Mortgage interest
- Property taxes
- Insurance
- HOA fees
- Repairs
- Maintenance
- Management fees
- Utilities
- Advertising
- Professional fees
- Supplies
- Software
- Eligible transportation and travel
Also record legitimate property expenses paid personally so they do not disappear from the books.
9. Establish the Depreciation Schedules
Once the appropriate basis and placed-in-service information are available, your CPA can establish depreciation schedules for qualifying assets.
Those schedules may include:
- Building
- Capital improvements
- Furniture
- Appliances
- Equipment
- Other qualifying depreciable assets
Different assets may have different recovery periods and placed-in-service dates.
Keep the depreciation schedules with your permanent tax records rather than treating them as documents relevant only to one year’s tax return.
10. Evaluate Cost Segregation Where Appropriate
If the property may be a good candidate for cost segregation, evaluate the strategy early.
Consider:
- Property value
- Depreciable basis
- Property components
- Renovations
- Investor tax position
- Ability to use additional losses
- Cost of the study
- Expected holding period
- Future disposition strategy
Do not order a study simply because another investor used one.
Ask your CPA to estimate whether accelerating depreciation is likely to create a meaningful economic benefit in your situation.
11. Begin Material-Participation Records if Relevant
If material participation or Real Estate Professional Status could affect your tax strategy, start documenting your activity immediately.
Maintain records showing:
- Date
- Property
- Activity
- Time spent
- Nature of work
Depending on the circumstances, activities might involve:
- Property management
- Tenant matters
- Contractor oversight
- Property inspections
- Leasing
- Other qualifying operational work
Do not wait until the following tax season and attempt to recreate an entire year of participation from memory.
12. Schedule Your Next Tax-Planning Review
Closing should not be the last time you speak with your CPA until tax season.
Schedule a follow-up based on the property’s activity.
The next review may cover:
- Renovations
- Actual rental income
- Operating expenses
- Depreciation
- Cost segregation
- Passive losses
- Material participation
- Estimated taxes
- Additional acquisitions
If you expect another major transaction—such as buying a second property, refinancing, adding a partner, or selling—contact your CPA before the transaction occurs.
Your First 30-Day Rental Property Checklist
Use this condensed checklist after closing:
☐ Save the complete closing file
☐ Establish bookkeeping
☐ Open appropriate property accounts
☐ Set up property-level tracking
☐ Record the acquisition correctly
☐ Establish land/building allocation
☐ Separate renovation projects
☐ Save contractor invoices and receipts
☐ Document the placed-in-service date
☐ Begin tracking income and expenses
☐ Establish depreciation schedules
☐ Evaluate cost segregation
☐ Begin participation records when relevant
☐ Track personal-use days when applicable
☐ Confirm Florida and local compliance requirements
☐ Schedule the next CPA tax-planning review
The objective during the first 30 days is not to implement every possible tax strategy. It is to establish clean records and accurate tax treatment from the beginning.
A property with correctly recorded basis, organized closing documents, properly classified renovations, accurate bookkeeping, documented placed-in-service dates, and contemporaneous participation records is much easier to manage than one that has to be reconstructed years later.
Your tax plan should therefore continue after closing. The purchase is simply the starting point for the property’s ongoing bookkeeping, depreciation, tax planning, and eventual exit strategy.
Tax Planning Before Buying vs. Tax Preparation After Buying
Tax planning and tax preparation serve different purposes. Tax preparation primarily reports transactions and decisions that have already occurred. Tax planning looks forward and gives investors an opportunity to evaluate the tax consequences before making decisions that may affect them for years.
For a first-time rental property investor, that difference can be significant.
| Before Buying — Tax Planning | After the Year Ends — Tax Preparation |
| Evaluate ownership structure | Report existing ownership |
| Plan bookkeeping | Reconstruct or review records |
| Analyze depreciation strategy | Calculate depreciation based on completed transactions |
| Consider cost segregation | Review the property and elections already made |
| Plan renovations | Classify completed expenditures |
| Establish land/building allocation | Apply available information to depreciation calculations |
| Evaluate passive loss limitations | Determine how current losses are treated |
| Consider Real Estate Professional Status | Determine whether requirements were satisfied |
| Plan short-term vs. long-term use | Report how the property was actually operated |
| Consider personal-use consequences | Allocate expenses based on actual use |
| Evaluate financing | Account for existing debt and financing costs |
| Consider exit strategy | Report completed transactions |
| Evaluate potential 1031 strategy | Report a sale or properly structured exchange |
| Estimate tax consequences | Calculate the actual tax liability |
| Make informed decisions while options remain | Prepare the tax return based on what occurred |
Why Does the Timing Matter?
Consider entity structure.
Before buying, you can evaluate whether the property should be purchased:
- Individually
- Through a single-member LLC
- Through a multi-member LLC
- With a partner
- Through another appropriate structure
After closing, the property already has an owner. Changing that structure later may involve additional legal, financing, insurance, administrative, and tax considerations.
The same principle applies to many other decisions.
Tax Planning Helps You Make Decisions Before They Become Transactions
Before purchasing, you can ask:
- How should the property be owned?
- How will financing affect the tax picture?
- What will the property’s basis be?
- How should land and building value be allocated?
- When will depreciation begin?
- Should cost segregation be evaluated?
- How should renovations be documented?
- Could passive activity limitations affect projected tax benefits?
- How should bookkeeping be established?
- What happens if I eventually sell or exchange the property?
At this stage, many decisions are still flexible.
You can compare alternatives before committing to one.
Tax Preparation Works With What Already Happened
When your CPA prepares the tax return after the year ends, many of those decisions have already been made.
The property has been purchased.
The loan has closed.
The entity owns the property.
Renovations have been completed.
Income and expenses have occurred.
Personal-use days have already happened.
The property may even have been sold.
Your tax preparer can determine the correct tax treatment and identify available opportunities, but preparation cannot always recreate planning opportunities that required action before the transaction.
Consider a Renovation Example
Suppose you purchase a property that requires $75,000 of work.
Before the renovation, you can establish procedures to:
- Document the property’s original condition
- Separate individual projects
- Obtain detailed contractor invoices
- Track repairs separately from improvements
- Record appliances and equipment separately
- Document completion and placed-in-service dates
- Evaluate depreciation implications
After the year ends, your CPA may instead receive:
Contractor — $75,000
with little explanation.
The work still needs to be classified correctly, but the lack of planning and documentation makes the process much more difficult.
Consider a Property Sale
The difference can become even more significant when selling.
Before selling, an investor can evaluate:
- Estimated taxable gain
- Adjusted basis
- Suspended passive losses
- Depreciation-related consequences
- Potential 1031 exchange
- Replacement-property strategy
- Timing
After the sale closes, some of those options may no longer be available.
A 1031 exchange, for example, generally needs to be structured before the investor receives control of the sale proceeds.
Tax preparation can report the completed sale correctly, but it cannot necessarily convert an already completed conventional sale into the transaction the investor wishes had occurred.
Tax Planning Does Not Mean Chasing Deductions
The purpose of planning is not to structure every investment around obtaining the largest immediate tax deduction.
A good rental property should first make economic sense.
Tax planning then helps investors understand how different choices affect:
- Current taxes
- Cash flow
- Depreciation
- Future deductions
- Administrative costs
- Portfolio growth
- Future property sales
- Long-term wealth strategy
Sometimes the strategy producing the largest first-year deduction may not be the strategy that best supports the investor’s long-term objectives.
The Main Takeaway
The difference can be summarized simply:
Tax preparation documents decisions. Tax planning helps investors make them.
Your CPA can provide value at both stages, but the opportunity to influence the outcome is generally greater before the transaction occurs.
That is why the ideal time to begin tax planning for your first Florida rental property is not when your first tax return is due.
It is before you buy the property.
Add a Stronger Investor-Focused Call to ActionTighten the Repetitive Paragraph Structure
How Can Cloud Accounting Group Help Before You Buy a Rental Property?
Cloud Accounting Group helps real estate investors evaluate the tax and accounting decisions surrounding a rental property before the purchase is complete. The goal is to establish the right tax strategy, bookkeeping system, and financial framework from the beginning rather than trying to correct avoidable problems after closing.
Pre-Purchase Tax Planning
Before you buy, we can help you understand how the proposed investment fits into your overall tax situation.
That can include reviewing:
- Expected rental income and expenses
- Projected tax results
- Passive activity considerations
- Planned renovations
- Financing
- Depreciation
- Short-term versus long-term rental use
- Personal use
- Future acquisitions
- Potential exit strategies
Tax planning should consider the entire investment rather than focusing solely on the first year’s deductions.
Entity and Tax Structure Analysis
How you own a rental property can affect tax reporting, bookkeeping, administrative costs, future partners, and long-term flexibility.
Cloud Accounting Group can help evaluate the tax implications of structures such as:
- Individual ownership
- Single-member LLCs
- Multi-member LLCs
- Partnerships
- Other applicable tax classifications
Legal entity selection also involves liability and asset-protection considerations, so we encourage investors to coordinate tax planning with a qualified attorney when appropriate.
Depreciation Planning
Depreciation can become one of the largest tax deductions associated with rental real estate.
We can help investors evaluate:
- Tax basis
- Land/building allocation
- Placed-in-service dates
- Building depreciation
- Capital improvements
- Furniture
- Appliances
- Equipment
- Other depreciable property
Establishing accurate depreciation records from the first year can prevent errors that otherwise follow a property throughout its ownership.
Cost Segregation Evaluation
Cost segregation can potentially accelerate depreciation by identifying qualifying property components that may have shorter recovery periods.
But it isn’t automatically the right strategy for every rental.
Cloud Accounting Group can help evaluate whether cost segregation warrants consideration based on factors such as:
- Property value
- Depreciable basis
- Property type
- Improvements
- Current tax position
- Ability to use additional losses
- Applicable depreciation rules
- Expected holding period
- Future disposition plans
The objective is to determine whether accelerated depreciation creates a meaningful economic benefit—not simply the largest possible deduction.
Bookkeeping Setup
Good tax planning depends on good records.
We can help establish a rental property bookkeeping system that properly tracks:
- Rental income
- Property-specific expenses
- Mortgage activity
- Security deposits
- Owner contributions
- Owner distributions
- Repairs and maintenance
- Capital improvements
- Fixed assets
- Multiple properties
Starting with clean books makes tax preparation easier while also giving you better information about the property’s actual financial performance.
Estimated Tax Planning
Buying a rental property can change your overall tax picture, particularly when combined with income from:
- W-2 employment
- Businesses
- Other rental properties
- Partnerships
- S corporations
- Investments
- Property sales
We can help estimate how the new investment may affect your projected tax liability and whether estimated tax payments or other planning adjustments should be considered.
Portfolio Planning
Your first rental property may eventually become the beginning of a much larger portfolio.
We can help you think beyond the first acquisition and consider questions such as:
- How should additional properties be owned?
- Should each property’s performance be tracked separately?
- How will multiple rentals affect bookkeeping?
- How might passive income and losses interact?
- When should entity structures be reevaluated?
- How could future acquisitions affect the tax strategy?
- What should be considered before selling or exchanging properties?
Building scalable accounting and tax systems early can make future growth considerably easier.
Ongoing Real Estate Tax Strategy
Tax planning should not stop after closing.
As your investment changes, your tax strategy may need to change with it.
Ongoing planning can include:
- Year-end tax reviews
- Depreciation analysis
- Cost segregation
- Passive activity loss planning
- Real Estate Professional Status
- Material participation
- Short-term rental planning
- New property acquisitions
- Refinancing
- Property sales
- 1031 exchanges
- Portfolio restructuring
The most valuable time to speak with your CPA is often before a major transaction occurs.
Talk With Cloud Accounting Group Before Your Next Real Estate Investment
If you’re preparing to purchase your first rental property—or add another property to an existing portfolio—talk with Cloud Accounting Group before you close.
We can help you evaluate the tax implications, establish accurate bookkeeping and depreciation records, and develop a proactive strategy designed around both the property you’re buying today and the real estate portfolio you want to build in the future.
Talk With Cloud Accounting Group Before Your Next Real Estate Investment.
Frequently Asked Questions About Tax Planning Before Buying a Florida Rental Property
Should I talk to a CPA before buying a rental property?
Yes. Speaking with a CPA before buying gives you time to evaluate ownership structure, depreciation, financing, bookkeeping, passive loss rules, and other tax considerations before the transaction is complete. Your CPA can also help you establish accurate records from the beginning and evaluate how the property fits into your long-term investment strategy.
Should I create an LLC before buying a rental property in Florida?
An LLC may make sense for some Florida rental property investors, but it is not automatically the best structure for everyone. An LLC’s legal structure and federal tax classification are separate considerations. Discuss tax implications with your CPA and liability, asset-protection, and legal ownership issues with a qualified attorney before purchasing the property.
Should I put my rental property in an S corporation?
Not automatically. S corporations can provide tax advantages for certain active businesses, but traditional rental income generally does not receive the same potential employment-tax benefit. Holding appreciating real estate in an S corporation can also create additional considerations when transferring property later. Evaluate the property’s activity and long-term strategy before choosing this structure.
When does depreciation start on a new rental property?
Depreciation generally begins when the rental property is placed in service, meaning it is ready and available for its intended rental use. This may differ from both the closing date and the date the first tenant moves in. A property undergoing substantial renovations after purchase may not be placed in service immediately.
Can I deduct expenses before my rental property is available to rent?
Some pre-rental expenses may receive different tax treatment depending on what the expenditure represents and when it occurs. Certain costs may be capitalized rather than currently deducted. Because purchasing, renovating, and preparing a property for rental can create several categories of costs, keep detailed records and have your CPA classify them appropriately.
Should I do a cost segregation study on my first rental property?
Possibly, but cost segregation is not automatically appropriate for every first rental. Consider the property’s depreciable basis, components, study cost, your current tax position, ability to use additional losses, expected holding period, and future disposition plans. Your CPA can estimate whether accelerating depreciation is likely to provide a meaningful economic benefit.
How should I track renovation expenses after buying a rental property?
Track each renovation separately and retain contracts, detailed invoices, receipts, payment records, completion dates, and placed-in-service dates. Distinguish repairs and maintenance from capital improvements, furniture, appliances, and equipment. Avoid recording an entire renovation as one generic expense because individual components may receive different tax and depreciation treatment.
Can rental property losses offset my W-2 income?
Not automatically. Rental real estate is generally subject to passive activity loss rules, which can limit whether rental losses offset wages or other nonpassive income. Active participation, income limitations, material participation, Real Estate Professional Status, and other factors can affect the result. Losses that cannot currently be used may generally be suspended and carried forward.
Should I open a separate bank account for my rental property?
A dedicated rental property bank account is generally a good bookkeeping practice because it separates rental income and property expenses from personal transactions. It simplifies reconciliation, documentation, and property-level reporting. If an LLC or other entity owns the property, maintaining separate financial activity can also help keep the entity’s transactions distinct from personal finances.
What documents should I keep after buying a rental property?
Keep the purchase contract, final closing statement, loan documents, appraisal, inspection report, property tax records, insurance documents, entity records, improvement and contractor invoices, and receipts for furniture and equipment. Some acquisition and improvement records should be retained long term because they can affect depreciation, adjusted basis, and eventual gain calculations.
What taxes do Florida rental property owners need to consider?
Florida rental property investors should consider local property taxes and, depending on the property’s use, Florida sales and use tax, tourist development taxes, and other local obligations. Short-term rentals can have additional requirements. Applicable taxes and registrations vary by property type, rental period, county, municipality, and how reservations are accepted.
Should I plan for a 1031 exchange when buying my first property?
You do not need to commit to a 1031 exchange when purchasing your first rental, but understanding the option can help with long-term planning. A future qualifying exchange may allow eligible gain to be deferred when moving from one investment property to another. Maintain accurate basis, depreciation, and improvement records from the beginning.
Where are the best places to buy a rental investment property in Florida?
The best Florida market for a rental investment depends on your strategy, budget, expected rental demand, property costs, insurance, taxes, local regulations, and whether you plan to operate a long-term or short-term rental. Before purchasing, compare both investment fundamentals and tax implications. See our Best Places to Buy a Rental Investment Property in Florida guide for markets to consider.